Slide Image #1
Slide Image #2
Slide Image #3
Slide Image #4
Slide Image #5
mlsrealtor

Blog

The Best Time To Buy a Home in 2026 Is Almost Here

The Best Time To Buy a Home in 2026 Is Almost Here
Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.

Yes, mortgage rates have been ticking up lately – and that’s creating some real challenges with affordability. No one’s arguing that. But there are also predictable trends that happen this time every year that can put some wind back in your sails.

According to research coming out of Realtor.com, nationally, the week of September 27 – October 3 will be the best time to buy this year for this very reason:

“The week of September 27–October 3 brings together the market conditions buyers value most—elevated inventory, less competition and prices that have eased from their seasonal high—giving prepared buyers a way to offset high rates with savings on price and room to negotiate with confidence.”

But that’s the national best week. Depending on where you live, your local sweet spot may come a little earlier or later (see map below):
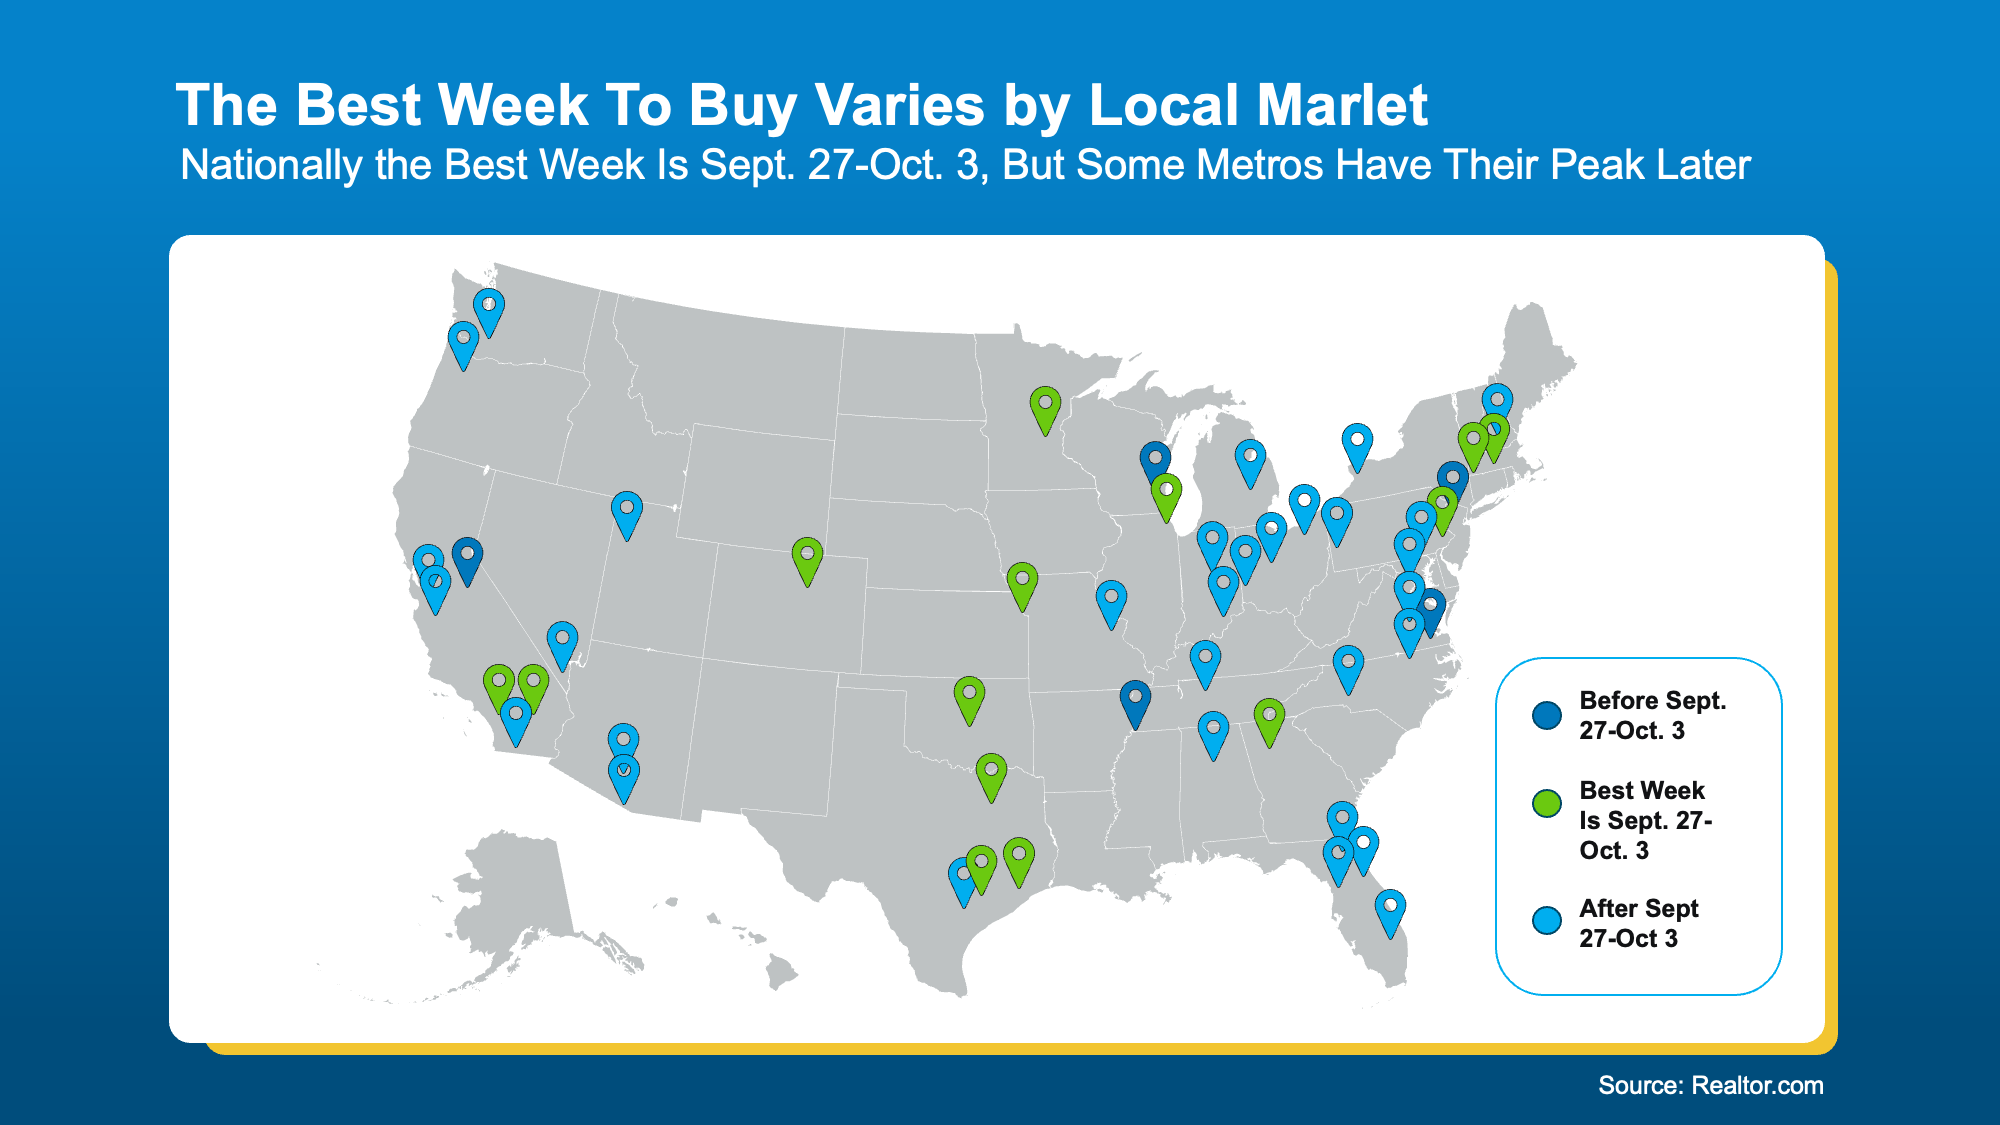
a map of the united states with pins

It all depends on local trends and how inventory and buyer demand ebbs and flows seasonally where you want to live. But no matter when your market hits its peak, here are some of the perks you can expect this time of year.

More Choices, Better Prices, and Less Competition

For starters, there are more homes to choose from. In fact, data from the National Association of Realtors (NAR) shows the number of homes for sale recently reached its highest level in more than 10 years:

“NAR’s data does show a strong uptick in for-sale inventory at the end of the summer, reaching the highest level in more than 10 years.”

That means you may have a better shot at finding something you love and can afford without making as many compromises. And that’s not the only advantage.

Realtor.com says buyers during this window could see home prices about $14,000 lower than the summer peak, along with 30% less competition from other buyers. Plus, homes tend to stay on the market almost 2 weeks longer (13 days), giving you a little more breathing room to make a decision.

  • More choices.
  • Better pricing.
  • Less competition.

That combination could be enough to ease some of the pressure higher mortgage rates are putting on your budget.

The Window Doesn’t Close After This One Week

But you certainly don’t have to buy during that very specific window. This isn’t a one-week-only opportunity. History tells us conditions should be tipped in your favor for the entire month of October:
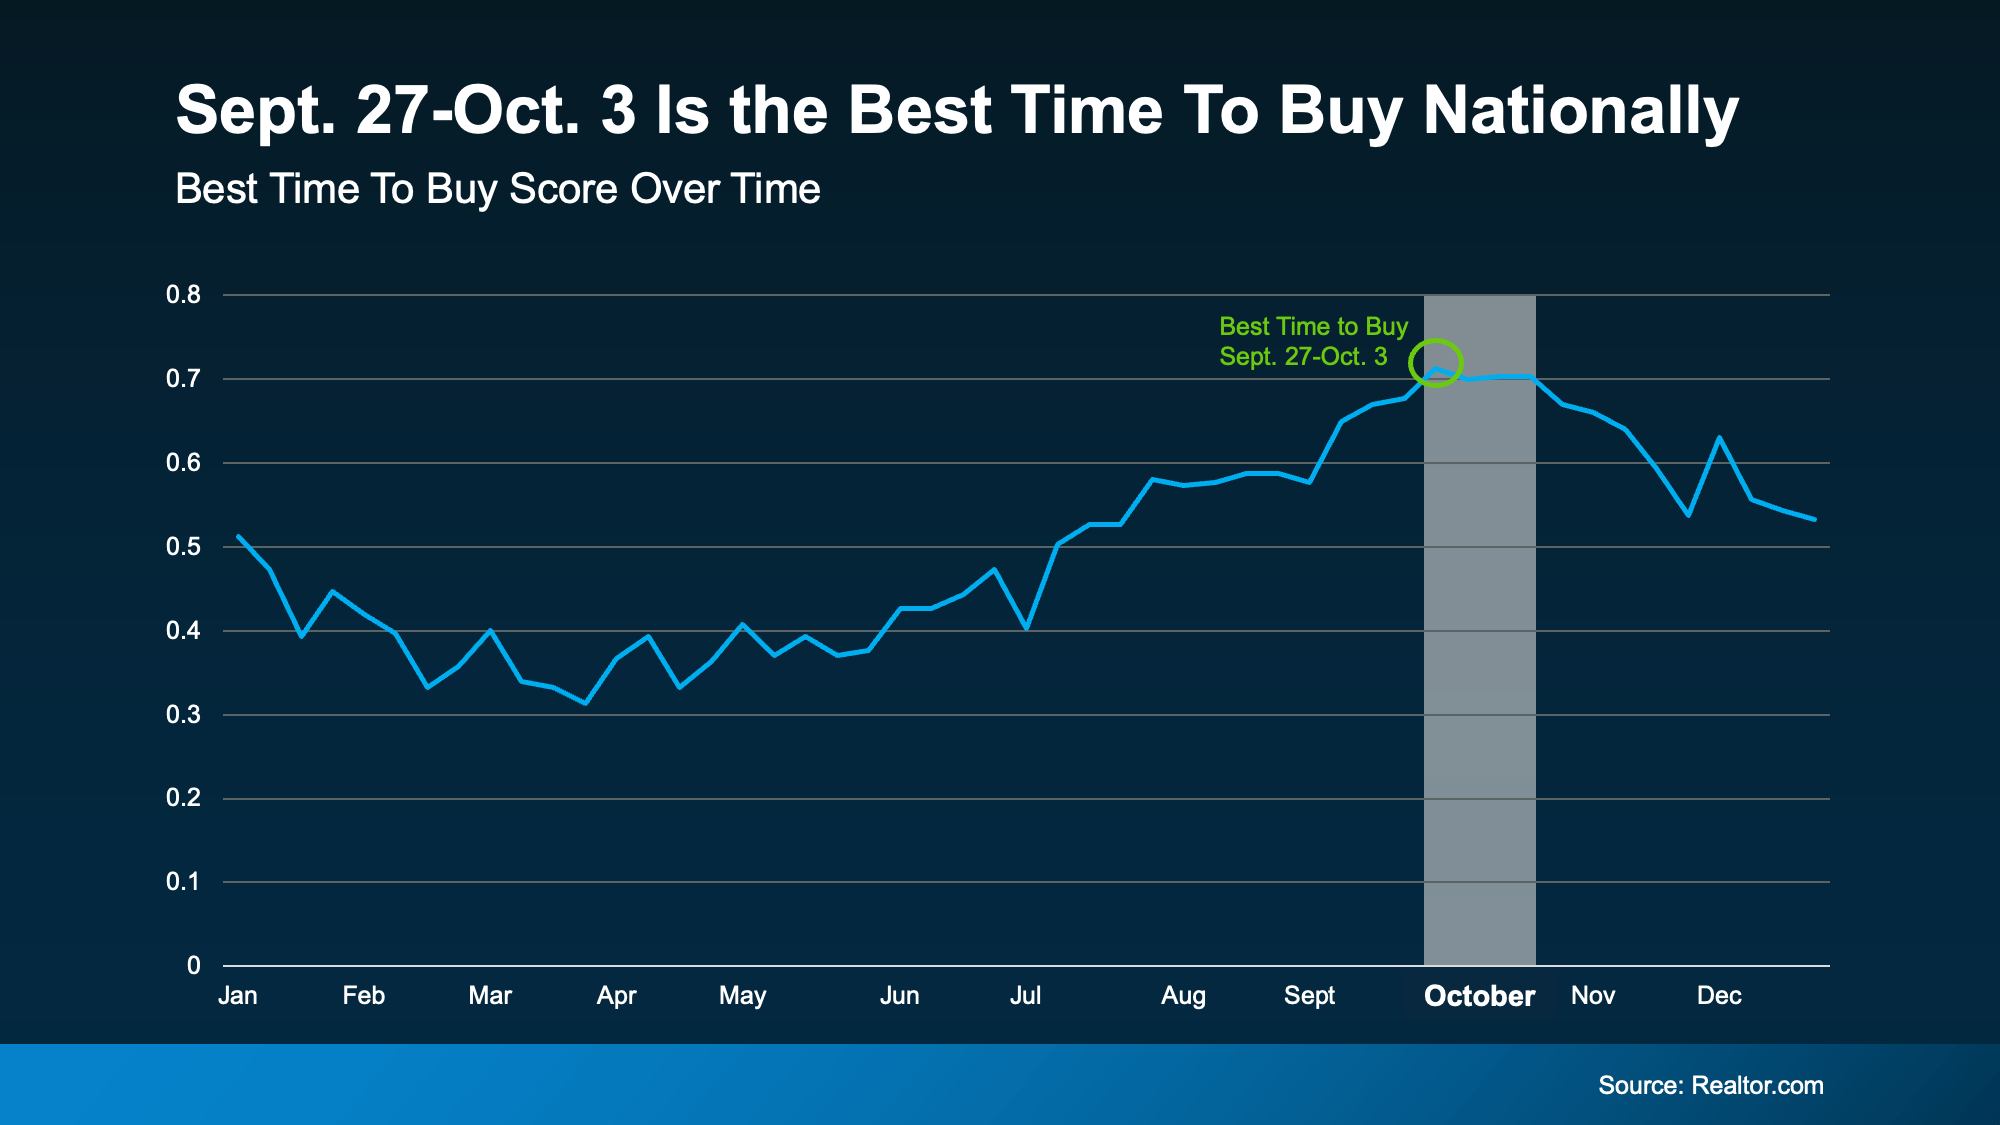
a graph on a dark background

In fact, Realtor.com says 42 of the 50 largest metros see their best week to buy fall sometime during October. So, don’t feel like you have to rush to hit one specific date. Use the time now to get things lined up, then jump in when the timing is right for you. As Guaranteed Rate explains:

“The best time to buy a home depends on your needs. Certain seasons can give you an advantage when starting your homebuying journey.”

Bottom Line

If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer.

Want help figuring out when those advantages typically show up in our market?

Let’s have a quick conversation about how our market works and the steps you’ll need to take to get ready.
Source: https://www.simplifyingthemarket.com/en/2026/09/16/the-best-time-to-buy-a-home-in-2026-is-almost-here?a=5256-fd674d1a840c47baa4da566e9ff662ab

One Number Could Change Everything About Your Next Move

One Number Could Change Everything About Your Next Move

When’s the last time someone told you what your house is worth? Not what some online valuation tool guessed. Not what your neighbor’s house sold for. What yours is actually worth right now.

For a lot of homeowners, it’s been years. And if you’ve been thinking about moving, but higher home prices or mortgage rates have made you hesitate, here’s why it’s time to take a second look at that number.

Your House May Be Worth More Than You Think

Home values have climbed significantly over the past 5-10 years. And even though today’s market is more balanced, homeowners are building wealth every day just by owning their homes. That’s how equity works. As home values rise, and as you make your monthly payments, your equity grows. And it adds up fast.

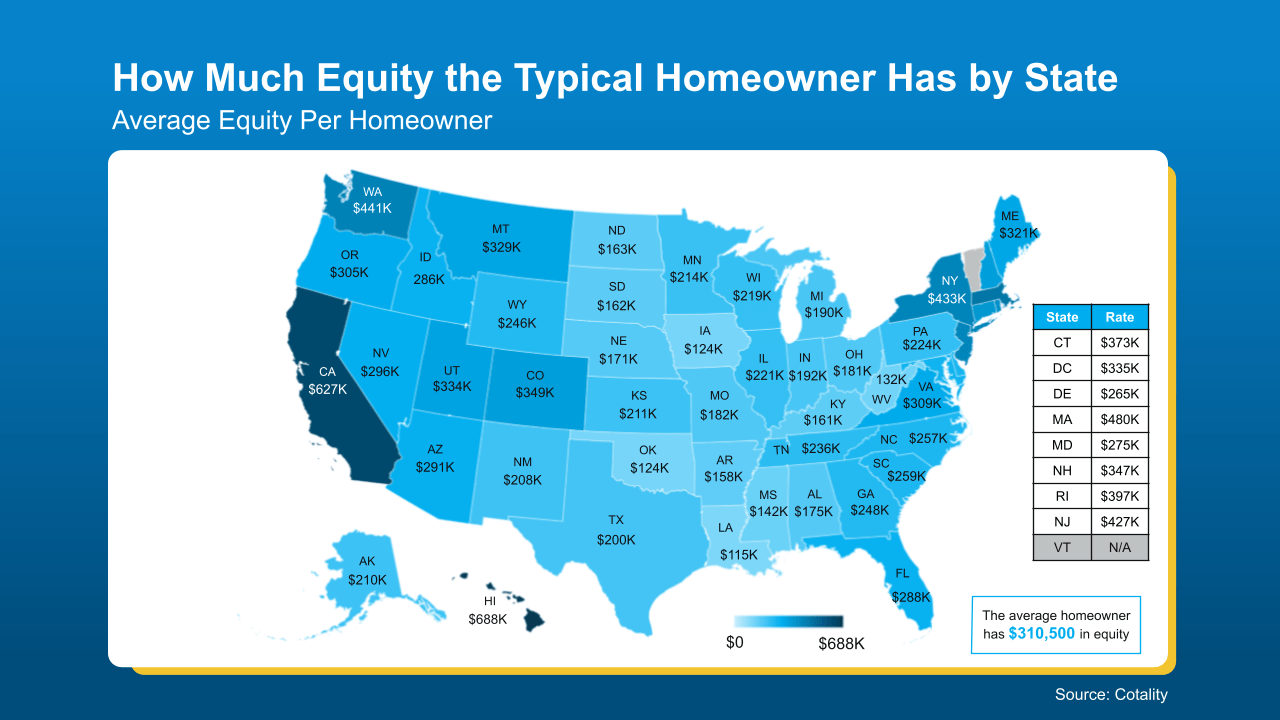
According to Cotality, the typical homeowner with a mortgage now has $310,500 in equity. That’s not a small number. It’s six figures.

And that’s only the national average. In many states, homeowners have built even more equity than that. Take a look at the map below and see where your state stands. The darker the blue, the more equity the typical homeowner has there (see map below):

a map of the united states

Even though every local market is different, the question you should be asking right now is the same: How much equity have you built up?

Because if you don’t know that number, you’re missing out.

This Could Be the Missing Piece in Your Move

Most people assume that because prices are higher and rates aren’t at 3% anymore, moving just isn’t realistic right now, especially if they already have an ultra-low rate. And that’s understandable – those are real factors.

But they’re not the only factors.

When you have that much equity in your house, you’re not starting from scratch. You’re not scraping together a down payment or hoping the numbers work. You’re walking into your next move with more of an advantage than you think. And that changes the math.

What Your Equity Can Do for You

Maybe you’ve outgrown your current house or you’re ready to downsize… The equity you’ve built could help bridge the gap between where you are today and where you want to be next.

Yes, your next house may cost more than your last one did. But your equity could cover a big chunk of that difference. Depending on how much you’ve built, it could help you:

  • Lower your monthly payment on your next home. The bigger your down payment on your next place, the less you have to borrow. And with today’s rates, borrowing less can make a big difference in what you pay every month.
  • Buy your next house with all cash. This surprises a lot of people, but some homeowners have built enough equity to buy their next home outright, in cash. According to the National Association of Realtors, more than one-quarter (26%) of repeat buyers paid all cash for their home in July.
  • Transform the home you already have. Love your neighborhood but not your floor plan? You don’t have to move. Your equity could help fund renovations that make your home fit your life today while potentially adding value for tomorrow.

Your equity doesn’t erase the challenges of the current market. But it does mean you’re walking into your next move with a lot more power and flexibility than you think.

That’s why the value of your home isn’t something you should have to wonder about. 

If you’re even thinking about a move – or if you’re just curious what your options might be – the smartest thing you can do is get a Professional Equity Assessment. It’ll give you a real, market-based evaluation of what your house is really worth right now and how much equity you’re working with.

Because once you see the number, maybe it’s not about whether you can afford to move – it’s about what kind of move makes sense for you.

Bottom Line

If it’s been a while since you’ve gotten a professional look at your home’s value, let’s change that.

Reach out for a free, personalized Home Equity Assessment that estimates what your house could sell for, how much equity you’ve likely built, and what that could mean for your next move.

Source: https://www.simplifyingthemarket.com/en/2026/08/20/one-number-could-change-everything-about-your-next-move?a=5256-fd674d1a840c47baa4da566e9ff662ab

Who Has the Upper Hand in Today’s Housing Market?

Who Has the Upper Hand in Today’s Housing Market?

Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal. And just about every seller wants to know if they’ll still get top dollar.

The interesting thing is… both can be right at the exact same time. It just depends on where you live.

That’s because today’s housing market isn’t moving in one direction anymore. Some markets clearly favor buyers. Others still favor sellers. But most are sitting somewhere in the middle.

And knowing which market you’re actually in can completely change the strategy you use to buy or sell (and what expectations you should have). Let’s break it down.

One Number Tells You Who’s Got Leverage

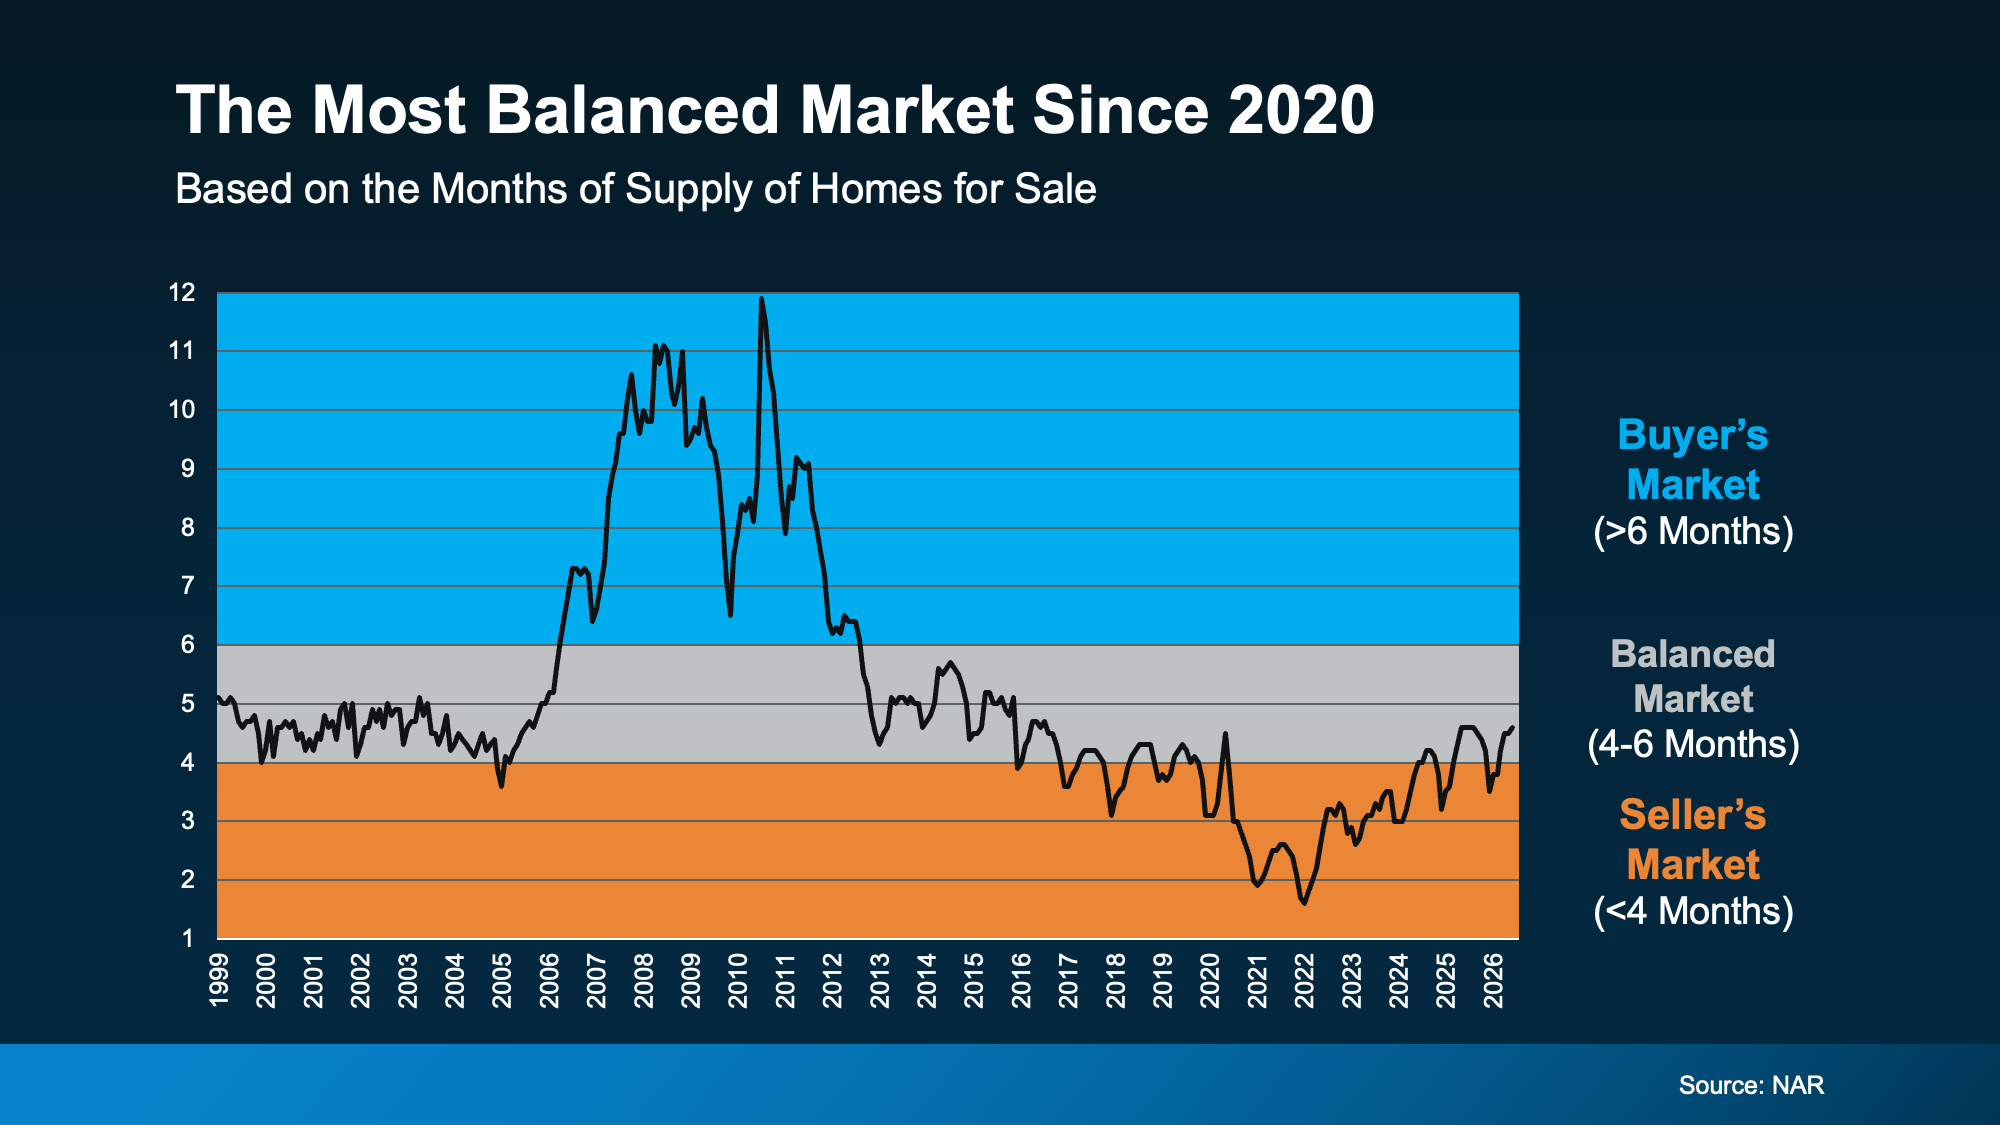
So how do you know which market you’re in? There’s one number that tells the story faster than anything else: the months’ supply of homes for sale. It’s the clearest signal of who’s got leverage – and what strategy you’ll need. Think of it like this.

Imagine no additional homes were listed starting today. Months’ supply tells us how long it would take to sell everything that’s currently on the market based on today’s demand.

Generally speaking, if months’ supply is:

  • Fewer than 4 months: Sellers usually have the advantage.
  • 4 to 6 months: Buyers and sellers are on more equal footing.
  • More than 6 months: Buyers can usually negotiate for a better deal.

Right now, the National Association of Realtors (NAR) data says that number is 4.6 and that puts the overall market back in balanced territory (see graph below):

a graph of a market

That means, as a whole, the market has finally moved back into a much more balanced range after years of being tilted in sellers’ favor. While that may look like the scales have tipped only slightly, it’s enough to make a real difference in what strategy you’ll need for your move – at least in most places.

The Tale of Two Markets: Why ‘Balanced’ Doesn’t Mean the Same Thing Everywhere

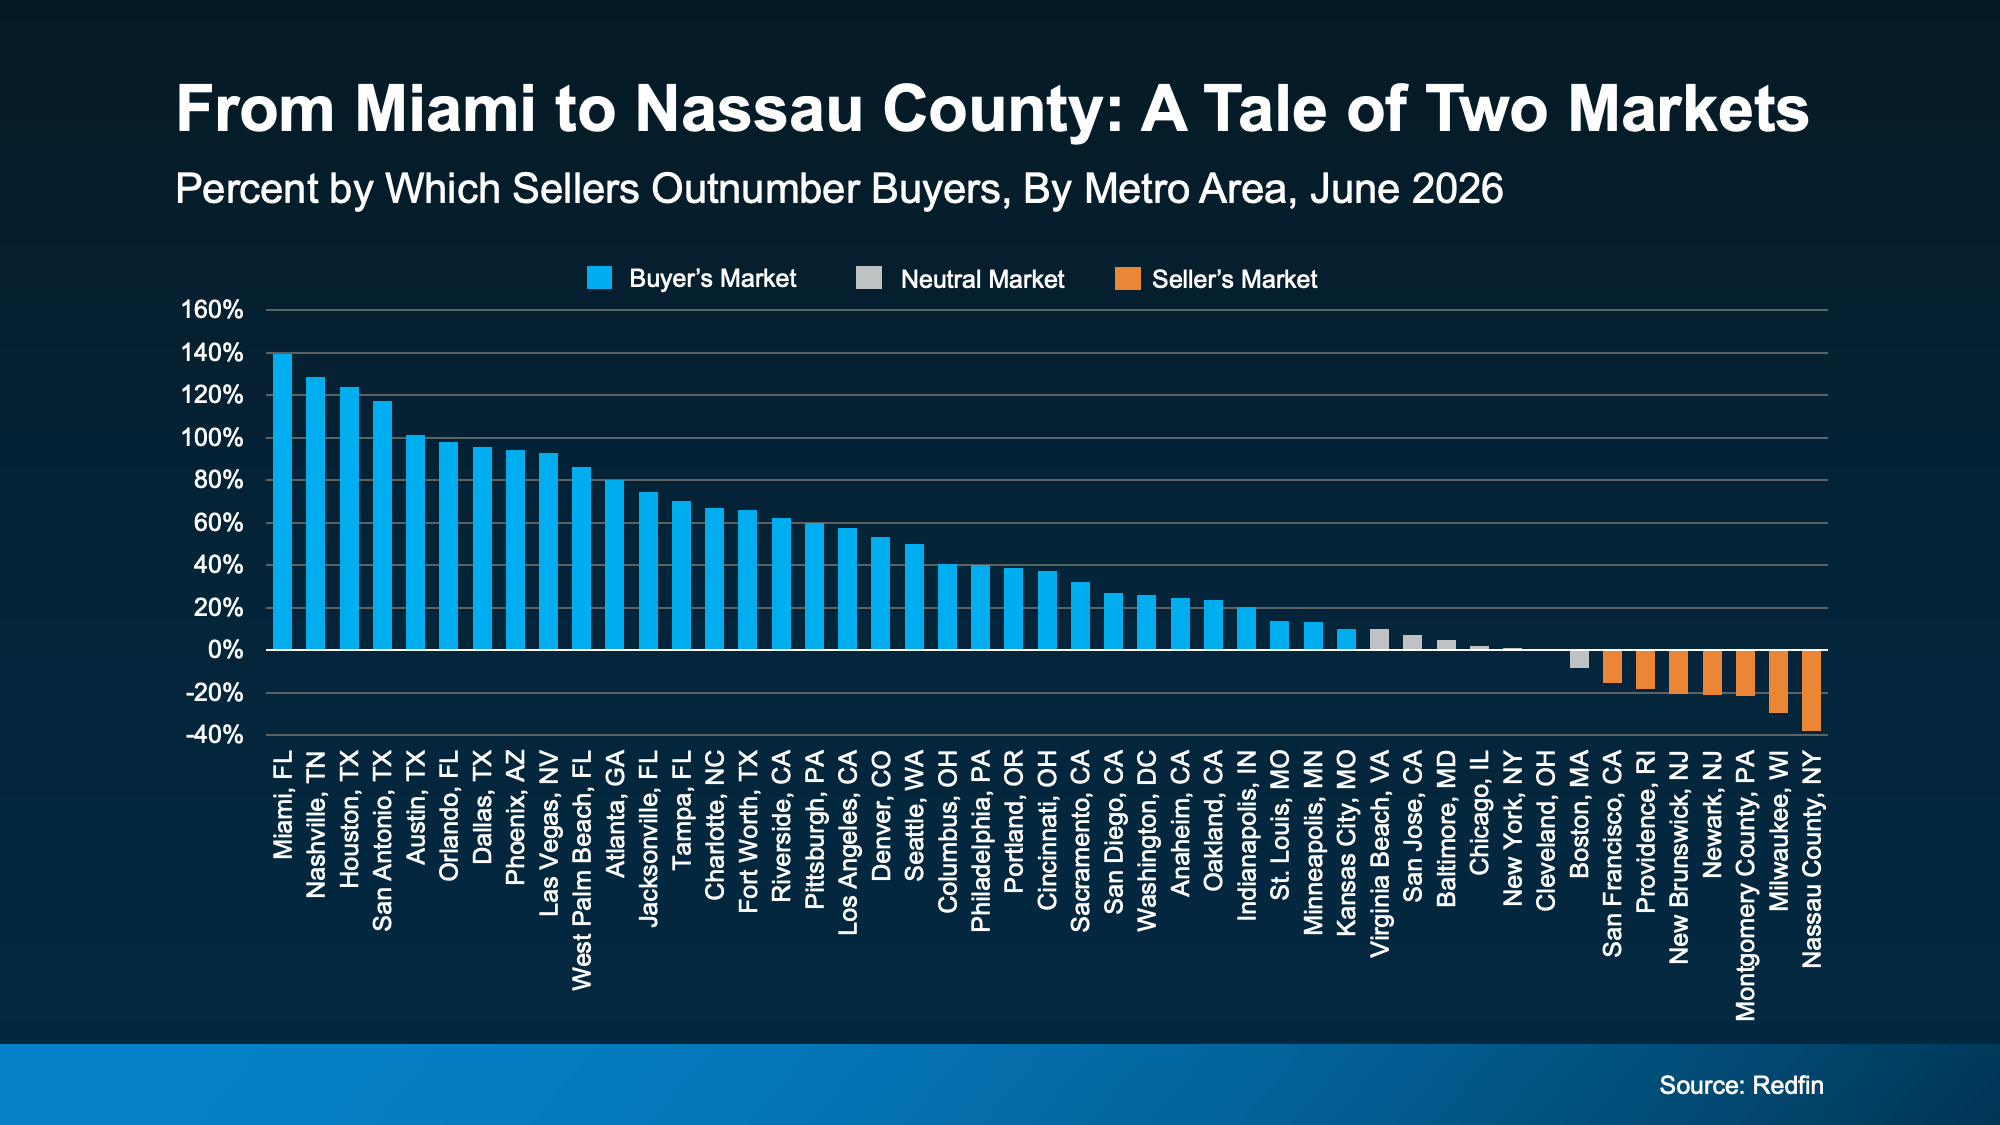
Redfin data helps shed some light on how this shakes out across the country. It breaks down which cities are leaning in either direction (see graph below).

  • Some markets give buyers more leverage. Those are in blue.
  • Some still favor sellers. That’s the orange.
  • Others fall somewhere in between. Those are gray.

a graph of a market

Notice anything? A lot more places are seeing more buyer-friendly conditions right now.  In fact, this is the most buyer-friendly market we’ve seen in nearly 6 years.

But don’t take that as buyers have the upper hand everywhere.

There are still cities where sellers still have the power. And if you’re in one of them, your approach to selling or buying looks completely different than it would in a buyer-leaning market.

The Biggest Mistake You Can Make Right Now

That’s why the biggest mistake isn’t thinking it’s finally a buyer’s market. And it isn’t thinking it’s still a seller’s market either. It’s making any assumption without talking to an expert agent first.

Today’s market is incredibly local. In one market, a buyer may be getting thousands of dollars in concessions from a seller. And a homeowner may have to consider dropping their price.

But in another, a buyer may be stressed about coming in with their best offer, or they may lose out on the home to another buyer. And a seller may still be seeing strong demand and prices inching higher.

Same overall housing market.

Very different experiences.

The truth is what’s happening in your back yard affects everything from pricing your house to making an offer to negotiating repairs or concessions. And that’s why an agent’s local knowledge matters more now than ever before.

Your plan has to be based on your neighborhood – and only an agent has the expertise to get that right.

Bottom Line

This market isn’t one-size-fits-all.

If you’re wondering who has the upper hand where we live, let’s talk. I’ll show you exactly what the numbers look like in our market – and what strategy gives you the best shot at getting what you want.

Source: https://www.simplifyingthemarket.com/en/2026/08/13/who-has-the-upper-hand-in-todays-housing-market?a=5256-fd674d1a840c47baa4da566e9ff662ab

Are Home Prices Going To Fall?

Are Home Prices Going To Fall?

It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”

With everything in the news, that concern makes some sense. No one wants to make a big financial decision at the wrong time. But here’s what’s important to know. You don’t want to get hung up on the few places seeing slight declines right now.

When you zoom out and look at the full picture, home prices usually rise over time.

What the Data Really Shows

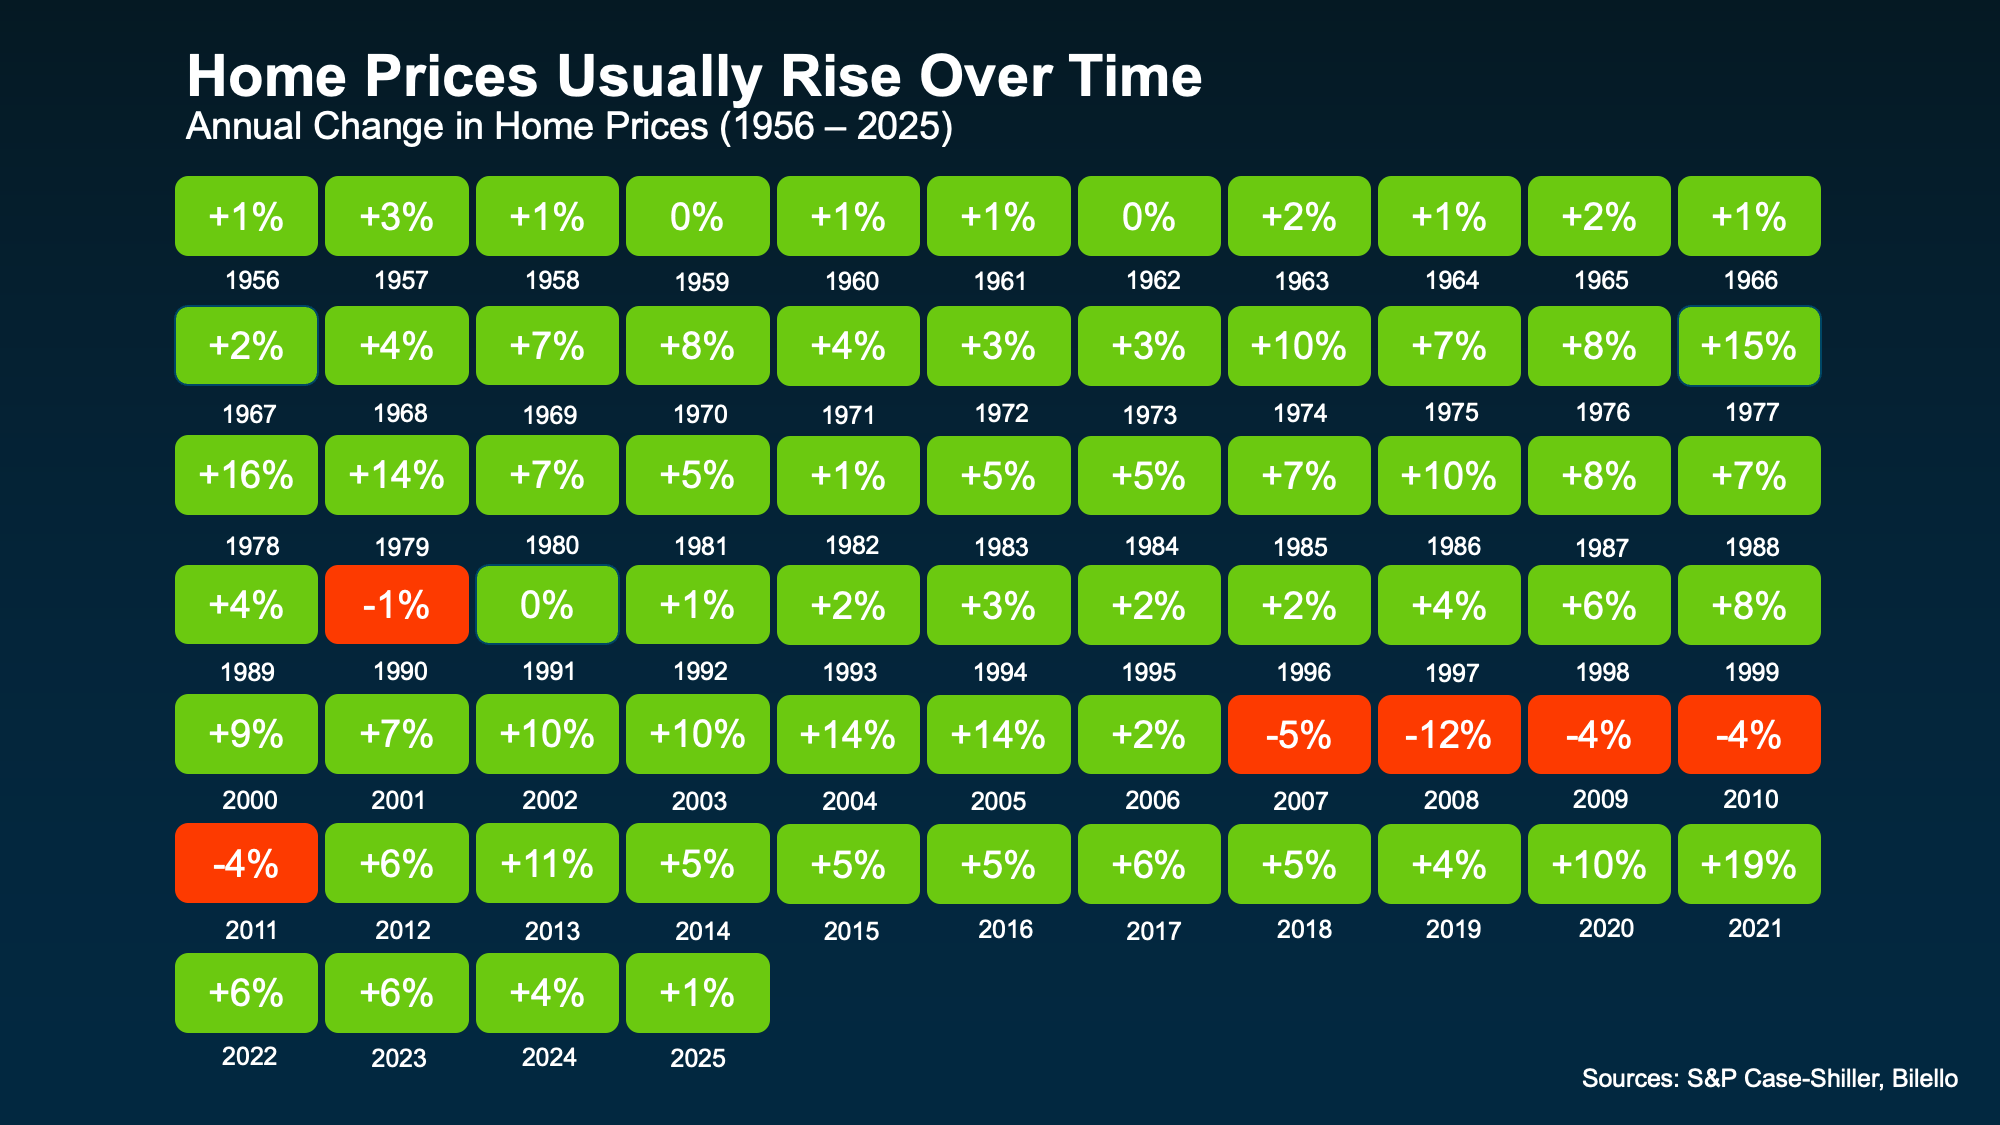
Take a look at the visual below. It uses data from Case-Shiller and Bilello to show how home prices have changed year by year going all the way back to the 1950s.

Here’s the key takeaway.

Outside of the housing crash, home prices have either held steady or increased in just about every year for decades (see visual below):

a chart of percentages and numbers

That’s a remarkably consistent track record. And it shows something a lot of headlines miss.

While short-term shifts can happen, it’s the long-term gains that really matter.

Why Prices Tend To Rise Over Time

There are a few core reasons prices usually go up each year:

  • There are always people who need to move. People need a place to live, and that demand will never fully go away. It may ebb and flow, but someone will always have to move as big changes happen in their life. So, homes stay in demand.
  • There still aren’t enough homes for sale. While the number of homes for sale has grown, nationally there’s still an undersupply based on how many people want a home. That keeps upward pressure on prices.
  • Inflation has an impact. Over time, the cost of goods (including homes) naturally increases. That pushes home values higher.

What That Means for You as a Buyer

It’s easy to get caught up in what might happen with home prices next month or next year, especially if you’re a first-time buyer and you’re feeling a little anxious about making such a big financial commitment. But the big picture is clear. Prices usually rise.

That doesn’t mean prices will go up every single year in every market. Real estate is local, and there can be short-term ups and downs. We’re seeing that in some places right now. You can even see it in the few annual dips in the visual above.

But historically, the declines have been temporary.

That’s why it’s generally recommended to buy a home only if you plan to stay for a while – typically at least five years. That’s normally enough time to see your house grow in value. And, it’s enough so you can ride out any short-term changes in the market.

Because when you can do that, something powerful happens. Those rising home values grow your net worth, and by extension, help you build wealth.

The right decision isn’t about timing the market perfectly. It’s about making a move that works for your life and staying in it long enough to benefit from the bigger trend.

Bottom Line

Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment.

That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while.

But if you’re interested, let this reassure you. If you want to talk through what home prices are doing in our market, your goals, or your timelines, let’s have a quick conversation.

Source: https://www.simplifyingthemarket.com/en/2026/05/18/are-home-prices-going-to-fall?a=5256-fd674d1a840c47baa4da566e9ff662ab

Rent or Buy? The Real Tradeoff Most People Don’t Talk About

Rent or Buy? The Real Tradeoff Most People Don’t Talk About

You’ve probably asked yourself lately: Is it even worth trying to buy a home right now? It’s a question a lot of people are asking.

With today’s home prices and mortgage rates, renting can feel like the easier path. In some cases, it might even seem like the only realistic option right now. And if that’s where you are, there’s nothing wrong with that.

But if you’re weighing the decision, there’s one part of the conversation that doesn’t get talked about enough.

It’s what each choice does for your future.

What Renting Really Gets You (And What It Doesn’t)

Depending on your situation, renting does have some advantages:

  • Lower upfront costs.
  • Less responsibility.
  • More flexibility to move when you want.

But even with those benefits, a Bank of America survey found 70% of aspiring homeowners worry about what long-term renting means for their future. And that concern comes down to one thing: you’re not building anything for your future. As Yahoo Finance explains:

“Paying rent doesn’t build equity. You get a place to live, but no ownership stake, no price appreciation, and no asset to leverage for future borrowing or investment.”

So, while renting may feel easier, the flexibility you get comes at a cost.

How Homeownership Builds Your Wealth Over Time

On the other hand, owning a home is one of the most consistent ways people build wealth over time. Why? When you’re a homeowner, you gain something called equity. That’s the difference between what your home is worth and what you owe.

That equity grows with every monthly payment you make. It also gets a boost as home values go up through the years – and it adds up quicker than you may think.

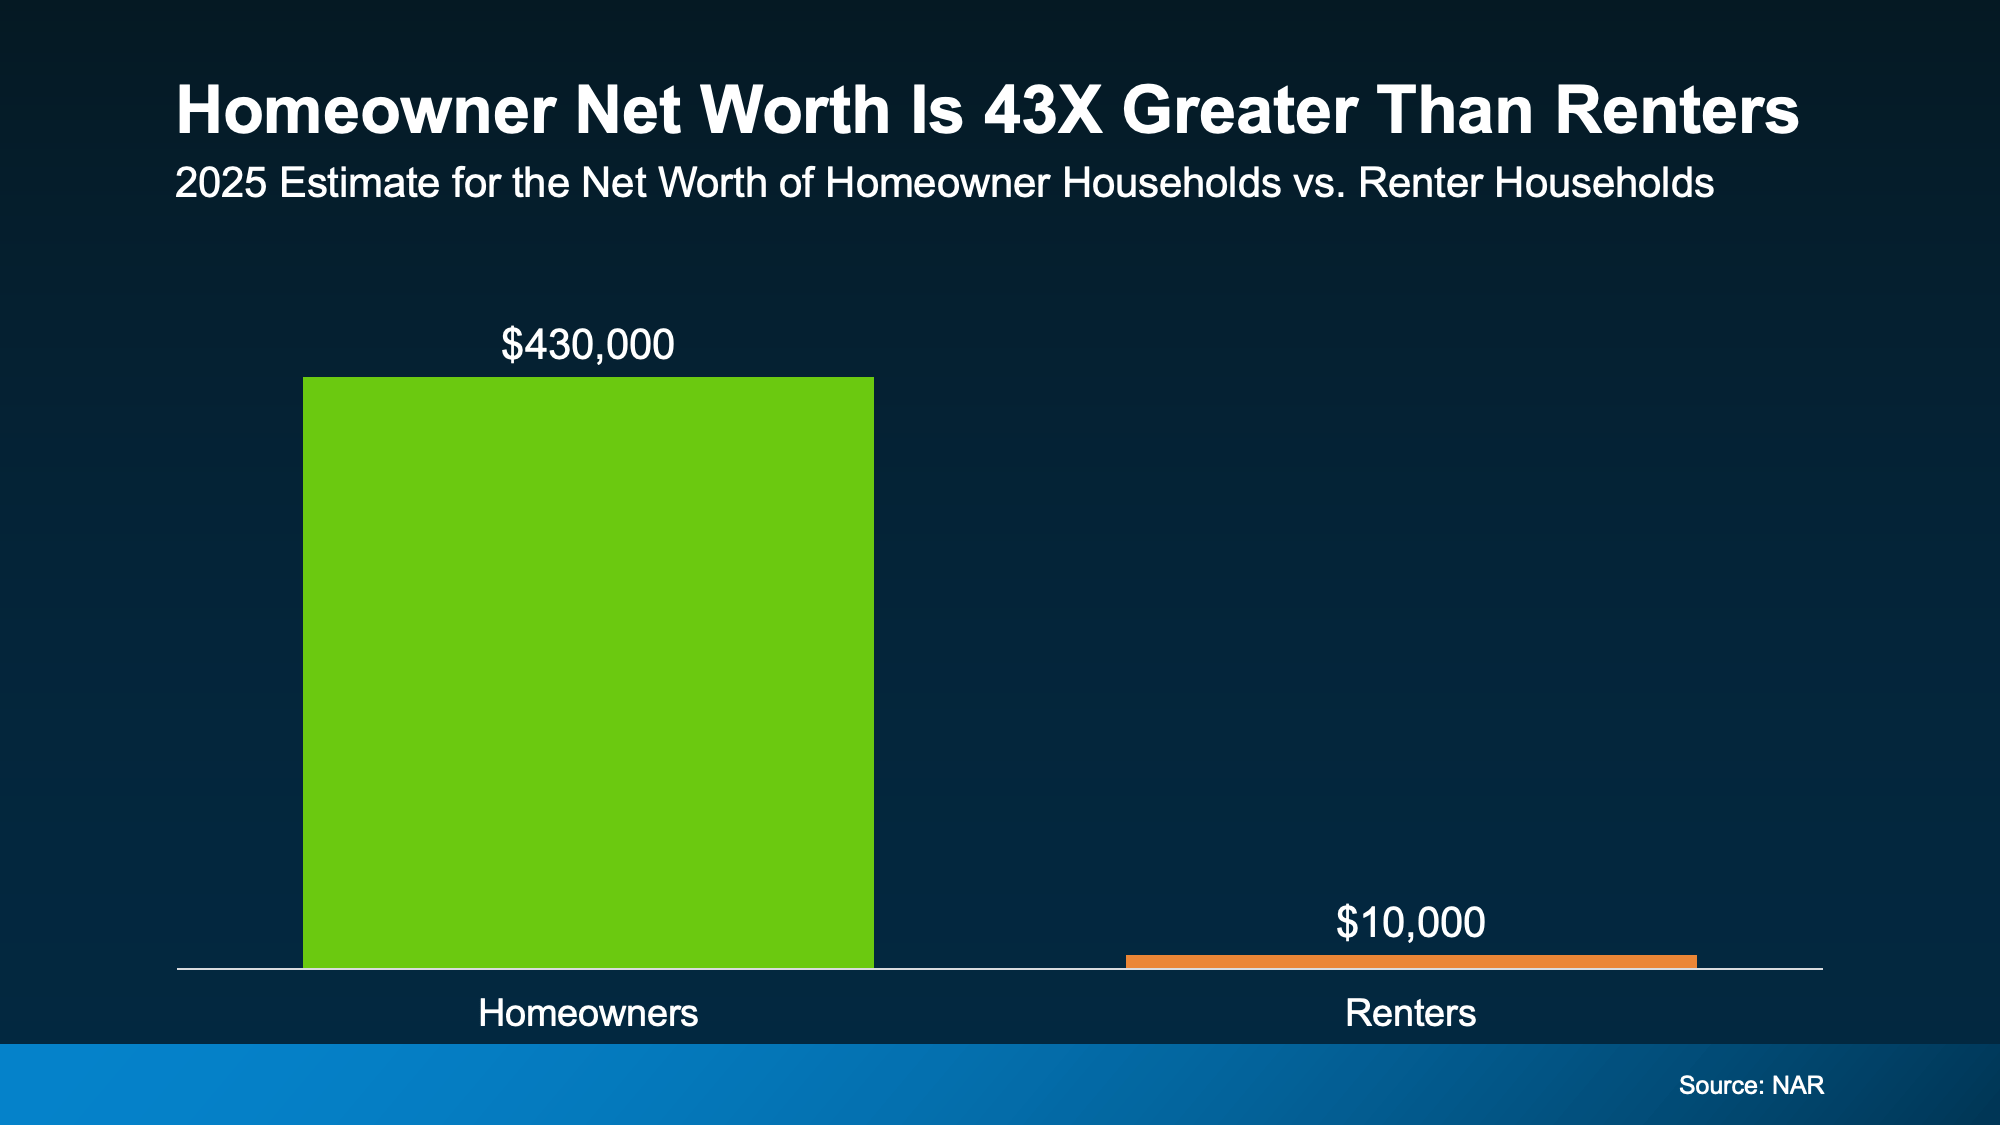
Today, the National Association of Realtors (NAR) says the average homeowner’s net worth is 43X greater than that of a renter:

a graph of a number of people

The dollars in the visual don’t lie. On average, here’s how net worth compares:

  • Homeowners: $430k
  • Renters: $10k

And it’s not because homeowners make wildly different decisions day to day. It’s because over time, one path builds something, and the other doesn’t.

So sure, buying comes with some upfront costs and more responsibility. But it’s basically a savings account you can live in.

The Gap Is Growing Over Time

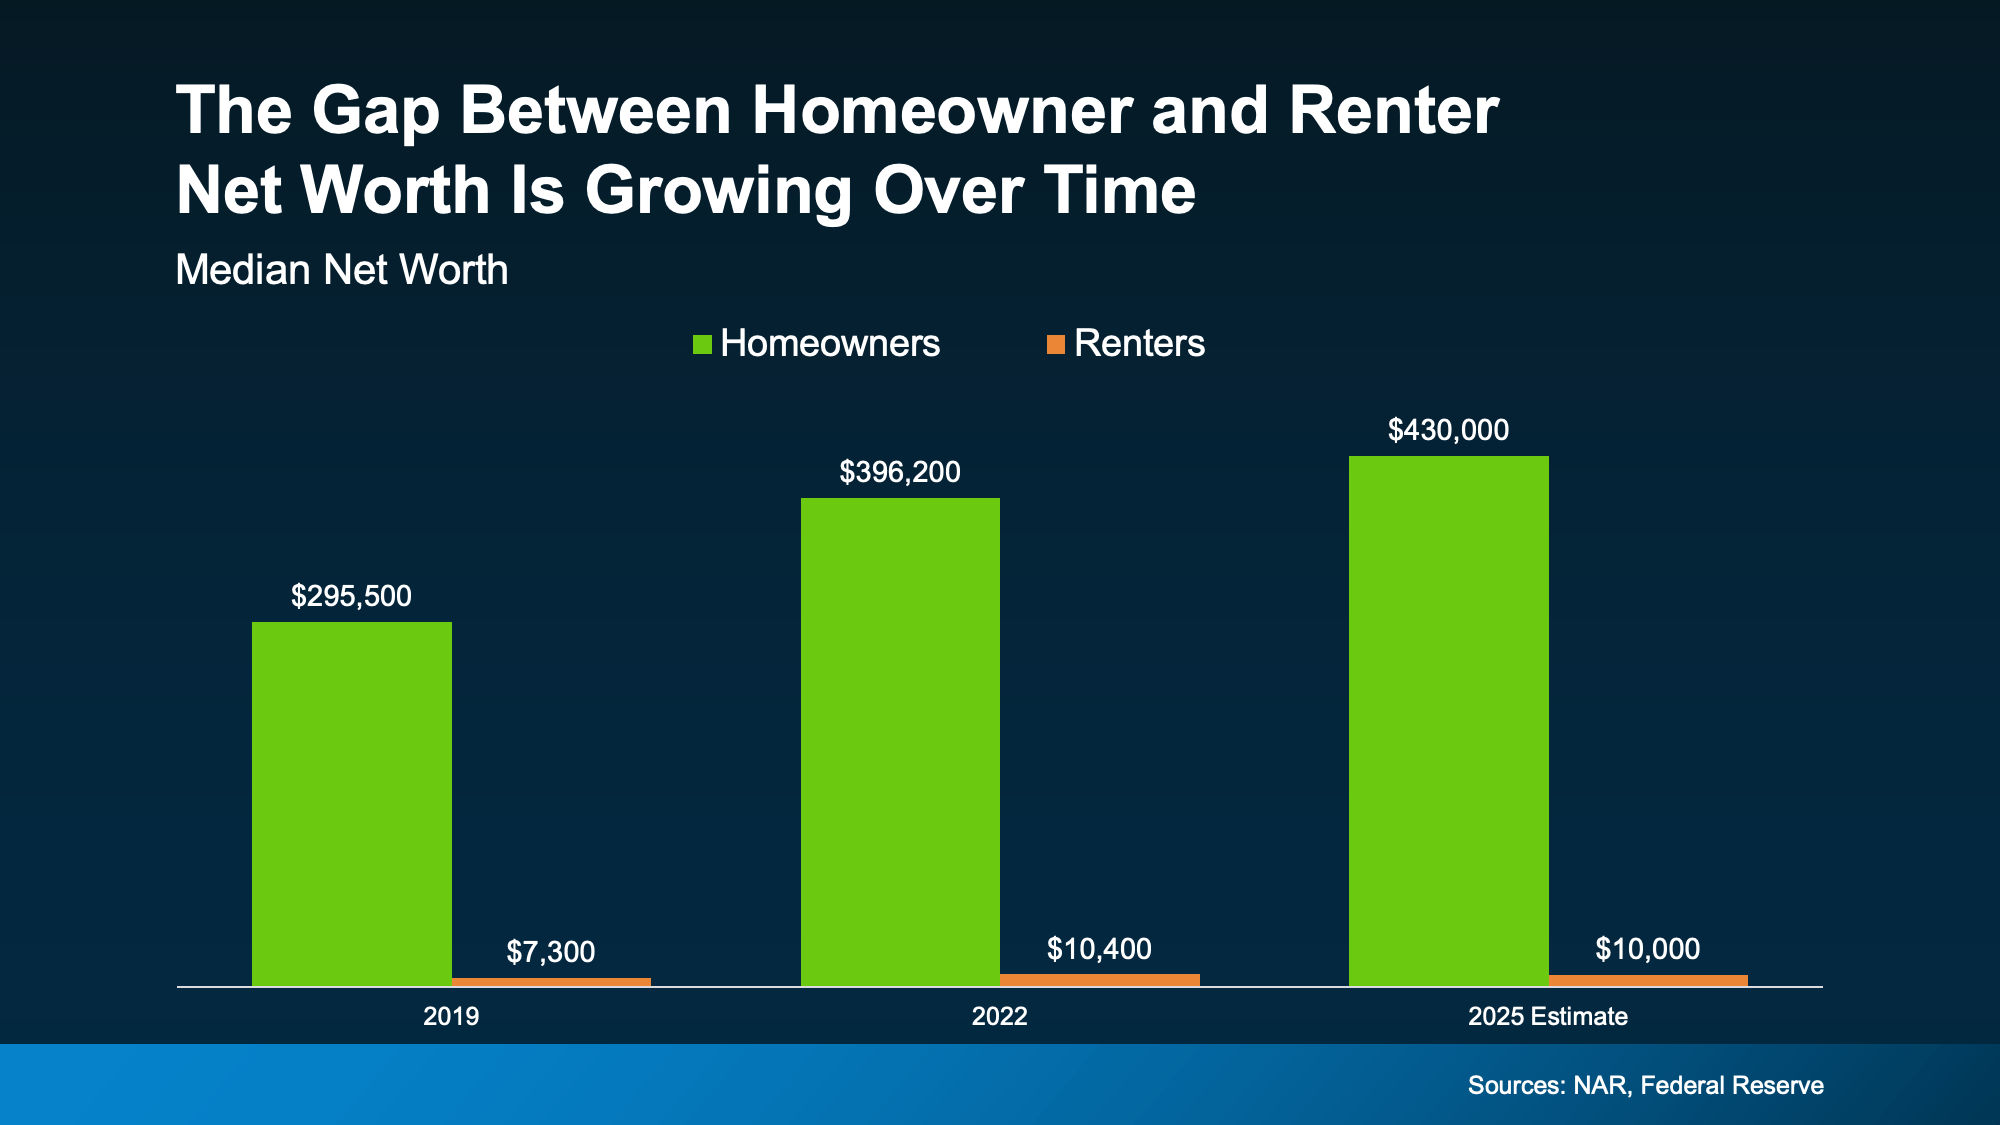
And here’s something else interesting. That net worth gap between renters and homeowners has been widening over time, not shrinking.

If you look back at the reports on net worth through the years, you can see the gap is growing as homeowners gain wealth and renters stay stuck in the rental trap (see graph below):

a graph of green and blue bars

Even in 2025, when home prices were moderating, homeowners still gained even more ground. And that tells you something important:

When you can afford it and you’re ready for the responsibility, history shows buying is usually worth it in the long run. Because either way, you’re paying for someone’s mortgage and building someone’s net worth.

When you rent, it’s your landlord’s mortgage – not yours. But when you buy? Your monthly payments help build equity.

The question is: whose do you want to pay? Yours or theirs?

So, Should You Buy a Home Now?

The short answer is, it depends on your situation.

While the long-term benefits of buying are clear, that doesn’t mean the timing is right for everyone right now. And that’s okay. You should only buy a home once you’re ready and the numbers work for you.

But whether you’re looking to buy now or planning for the future, the first step is the same. You should have a quick conversation with a local real estate agent about your goals, timeline, and budget.

They can help you run the numbers and see what’s realistic. You may find buying is closer than you thought. And if not, you’ll at least know exactly what it will take to get there.

Because the sooner you have a plan, the sooner you can decide when it makes sense, instead of wondering if it ever will.

Bottom Line

Renting may feel more do-able today. But over time, it could cost you.

If you want to ditch renting and start building something for your future, it starts with a simple conversation. Let’s connect, talk about your specific goals, and explore your options – so you’re ready when the time is right for you.

Source: https://www.simplifyingthemarket.com/en/2026/04/16/rent-or-buy-the-real-tradeoff-most-people-dont-talk-about?a=5256-fd674d1a840c47baa4da566e9ff662ab

When Buying a Home Feels Out of Reach, Some Families Do This Instead

When Buying a Home Feels Out of Reach, Some Families Do This Instead

For a lot of people, the math on buying a home just doesn’t really work right now. Maybe that’s how it feels for you too. You look at the cost of buying. Then you look at the cost of childcare. And it starts to feel like you have to choose one or the other.

But some families are finding a way to make both work by doing something a little different: teaming up to purchase a multi-generational home.

One Reason This Is Becoming More Common

It’s no secret that affordability has been a challenge in recent years. But for families with young kids, there’s an added layer that can make it feel even harder: childcare.

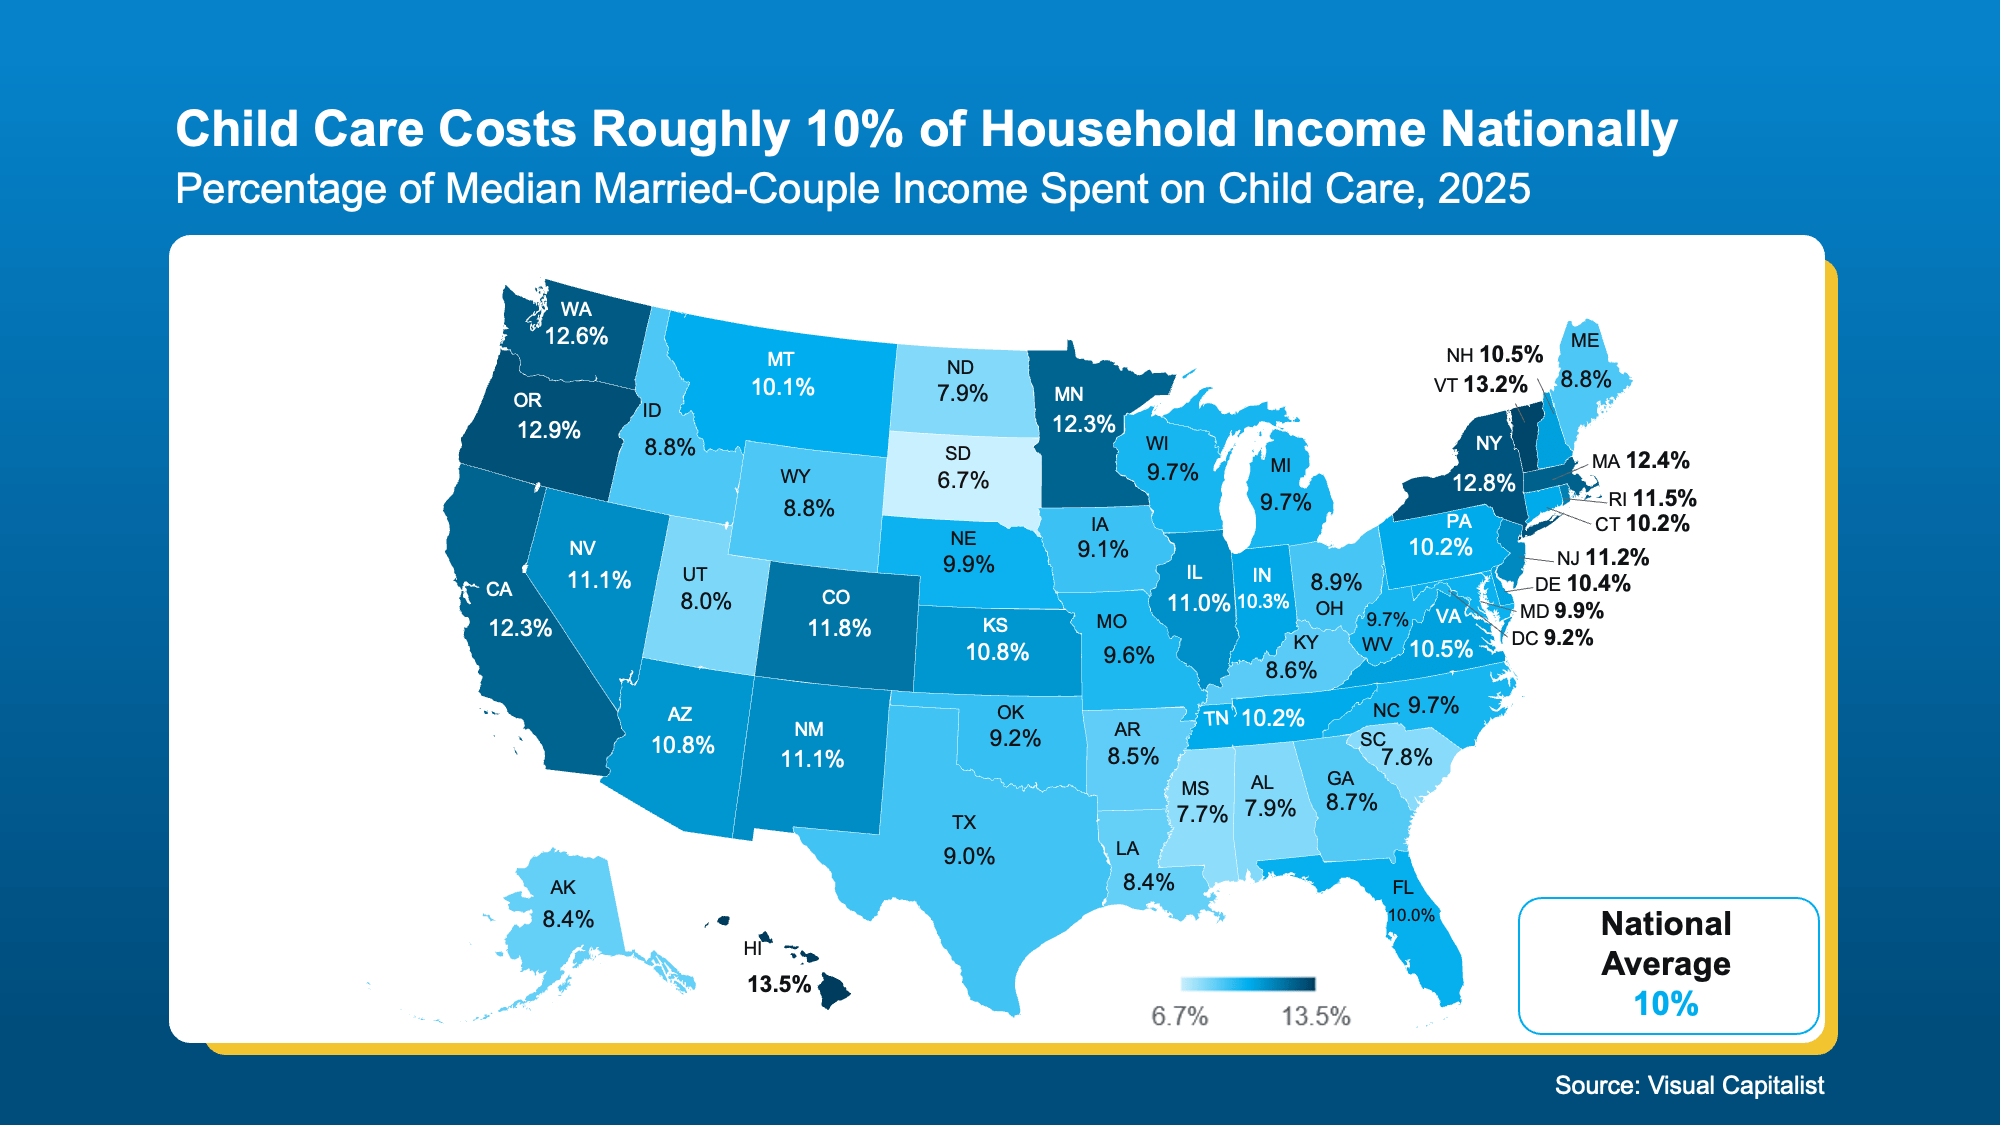
According to the Department of Health and Human Services, childcare should take up no more than 7% of your monthly income. But in reality, the average married couple spends closer to 10% (see map below):

a map of the united states

When you combine that with the cost of buying a home, it’s easy to see why things can feel stretched. That’s exactly why more families are starting to rethink how they approach both.

The Solution More People Are Turning To: Multi-Generational Living

One option gaining traction? Multi-generational living. That’s when parents, grandparents, or other relatives buy a house together and live under the same roof. And it’s not just about convenience anymore. It’s becoming a go-to strategy.

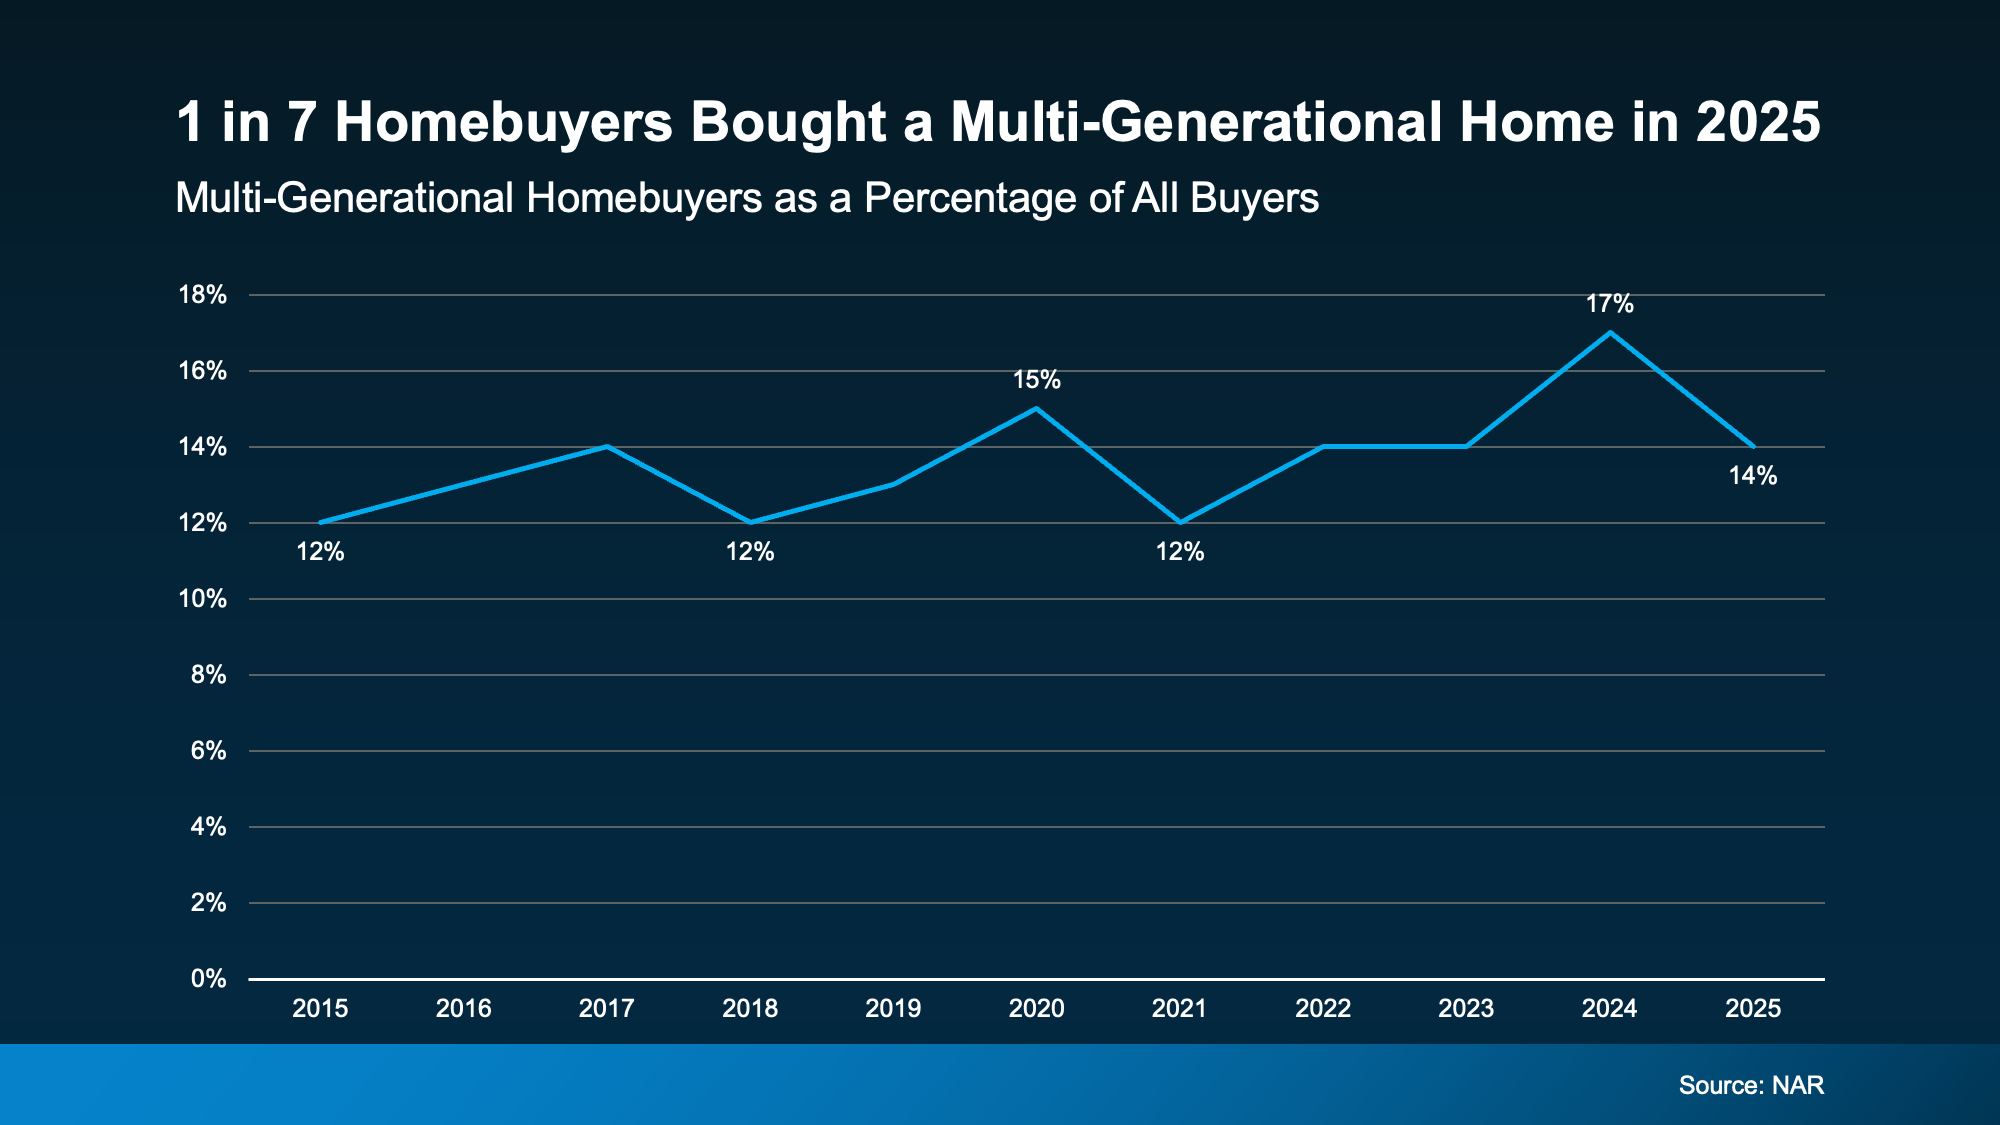
You can see it in the data. According to the National Association of Realtors (NAR), almost 1 in 7 homebuyers (14%) bought a multi-generational home in 2025 (see graph below):

a graph of a homebuyers bought a multi-generation home

And for the first time, childcare is showing up as a key reason why they chose this option. As NAR explains:

“This year’s report features two new primary reasons for purchasing a multi-generational home: grandchildren living in the home (12%) and to help reduce the cost of childcare (6%).”

Why It Works

Buying a multi-generational home solves two big challenges at the same time.

  • First, it shares the financial responsibility. If you pool multiple incomes together, you may be able to afford a home you couldn’t have on your own.
  • Second, it can also solve the childcare puzzle. When grandparents or other relatives live in the home, they may be able to help with daily care – which can significantly reduce or even eliminate daycare costs.

And for many people, that combination is what finally makes their move possible.

If the costs of childcare and housing together have made buying feel out of reach right now, it may be worth exploring creative options like buying a home with your loved ones.

Bottom Line

If you want more information on multi-generational homes, let’s have a quick conversation about what’s available in our area.

Sometimes the path to homeownership isn’t doing it alone. It’s doing it together.

Source: https://www.simplifyingthemarket.com/en/2026/04/09/when-buying-a-home-feels-out-of-reach-some-families-do-this-instead?a=5256-fd674d1a840c47baa4da566e9ff662ab

3 Must-Do’s for First-Time Home Buyers

3 Must-Do’s for First-Time Home Buyers

Buying your first home is exciting, but it can also be a little nerve-wrecking because it’s something you’ve never done before. And trying to think of everything you need to do can feel like a lot. But here’s the key.

You don’t have to figure everything out on your own. And you don’t have to do it all at once. Just tackle it one thing at a time.

Here’s a simple list of 3 main things you should focus on to help you get started.

1. Assemble Your Team: Don’t Do This Alone

Buying a home is a team sport. And having the right professionals by your side can make a world of difference. Here’s who you need to find:

  • A local real estate agent is your guide from the first showing to closing day. They’ll make sure you understand all the details along the way, so you feel confident in your decision.
  • A trusted lender will walk you through loan options, monthly payments, and what’s realistic for your situation. That information is something you’re going to want early on.

2. Prep Your Finances: Set the Foundation First

This is what determines what you can afford, how competitive you’ll be, and how confident you’ll feel when it’s time to make an offer. Here’s how to get ready:

  • Check your credit score. Your credit score impacts the loan options you’ll qualify for and even the mortgage rate you’ll get. Knowing this number early gives you time to work on raising your score, if you want to.
  • Save for your down payment and closing costs. Most buyers focus on the down payment, but closing costs matter too. Having savings set aside for both helps you avoid last-minute stress and surprises.
  • Look into assistance programs. Many first-time buyers qualify for programs that’ll give their homebuying savings a boost. This can make buying possible sooner than you expect.
  • Talk to a lender about mortgage options. Fixed-rate, adjustable-rate, FHA, VA, and conventional loans all work differently. Understanding the options helps you choose what fits your goals best.
  • Get pre-approved. A pre-approval tells you what a lender would be willing to give you for your home loan. This’ll help you figure out your price range and set you up to move fast when the right home comes along.
  • Figure out your budget. Your mortgage is just one part of homeownership. Budgeting for your utilities, home insurance, and everyday expenses and maintenance will help make sure your payment feels comfortable, not stressful.

3. Gather Your Documents: Save Time (and Stress)

When you’re officially ready to kick off the buying process, lenders are going to need to verify your income, assets, and financial history. Having these documents ready-to-go upfront can speed up the process and reduce back-and-forth. Here’s what Bankrate says you need to prep:

  • W-2s and tax documents (past 2 years). These show income stability and help lenders verify your earnings over time.
  • Recent pay stubs (generally the past 1–2 months). Pay stubs confirm your current income and employment status.
  • Bank statements (past 2–3 months). These show your savings, spending patterns, and where your down payment funds are coming from.
  • Investment account statements (past 2-3 months). If you’re using investments as part of your financial picture, lenders may ask for these as well.
  • Copy of your driver’s license. This verifies your identity and is required for loan processing.
  • Residential history (past 2 years). Lenders use this to confirm stability and background information.
  • Statements for any outstanding debts (past 2 months). Student loans, auto loans, and credit cards affect your debt-to-income ratio, so lenders will want to know about them.
  • Proof of supplemental income. Bonuses, commissions, side work, or child support may count toward your income if documented properly.

Note: the exact time frames and list of documents may vary lender to lender. This is just a general rule of thumb to help you get the ball rolling.

Bottom Line

Buying your first home doesn’t mean you have to have everything figured out. It just requires a plan.

If you start with your finances, organize your documents, and surround yourself with the right people, you’ll be in great shape when the time comes to make a move.

And if you want more information on anything in this list or just need help getting started, don’t hesitate to reach out.

Source: https://www.simplifyingthemarket.com/en/2026/03/18/3-must-dos-for-first-time-home-buyers?a=5256-fd674d1a840c47baa4da566e9ff662ab

Should You Wait for Lower Rates?

Should You Wait for Lower Rates?

Mortgage rates have already dropped into the upper 5s twice this year. But after just a few days, they ticked back up into the low 6% range. If you saw that and thought, “Great. I missed it,” you’re not the only one.

A lot of buyers are treating the 5s like some kind of magic number. As if moving from 6.1% to 5.99% suddenly changes everything. And from a mindset perspective, it does feel different.

But here’s the part most people don’t actually run the math on.

The Payment Difference Isn’t What You Think

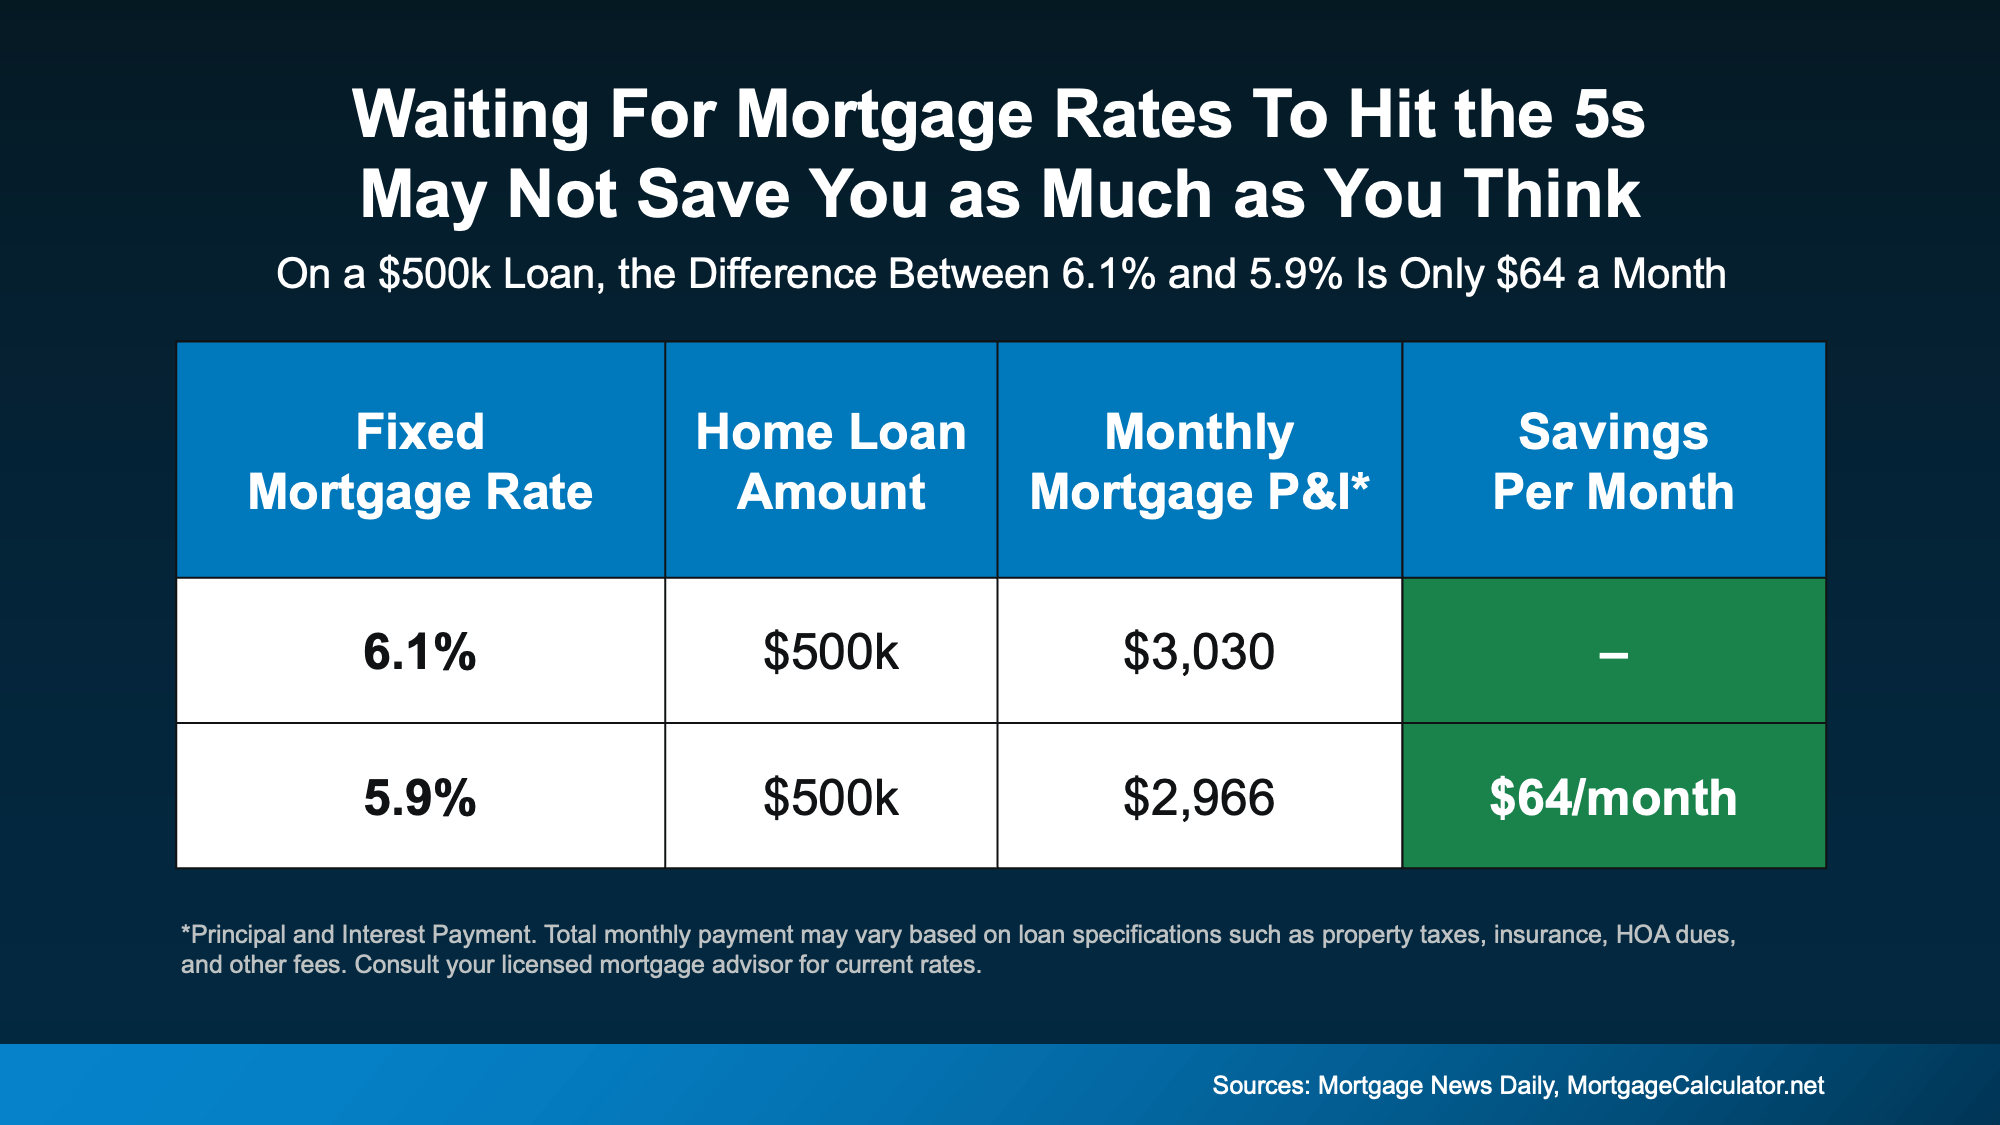
Let’s say you’re looking at a $500,000 home loan. At 6.1%, generally speaking, your principal and interest payment is roughly $3,030 per month. At 5.9%, it’s about $2,966 per month.

That’s a difference of only $64 a month.

Not $300.

Not $500.

Sixty dollars.

Let that sink in for just a moment.

a blue and green rectangular box with white text

Yes, over time that $64 a month can add up. But it’s far from the dramatic swing many buyers imagine when they say they’re “waiting for the 5s.”

The psychological impact of seeing a 5 in front of your rate can feel big. The financial impact? It might be something you don’t even notice when it’s all said and done.

Experts Aren’t Predicting a Big Drop

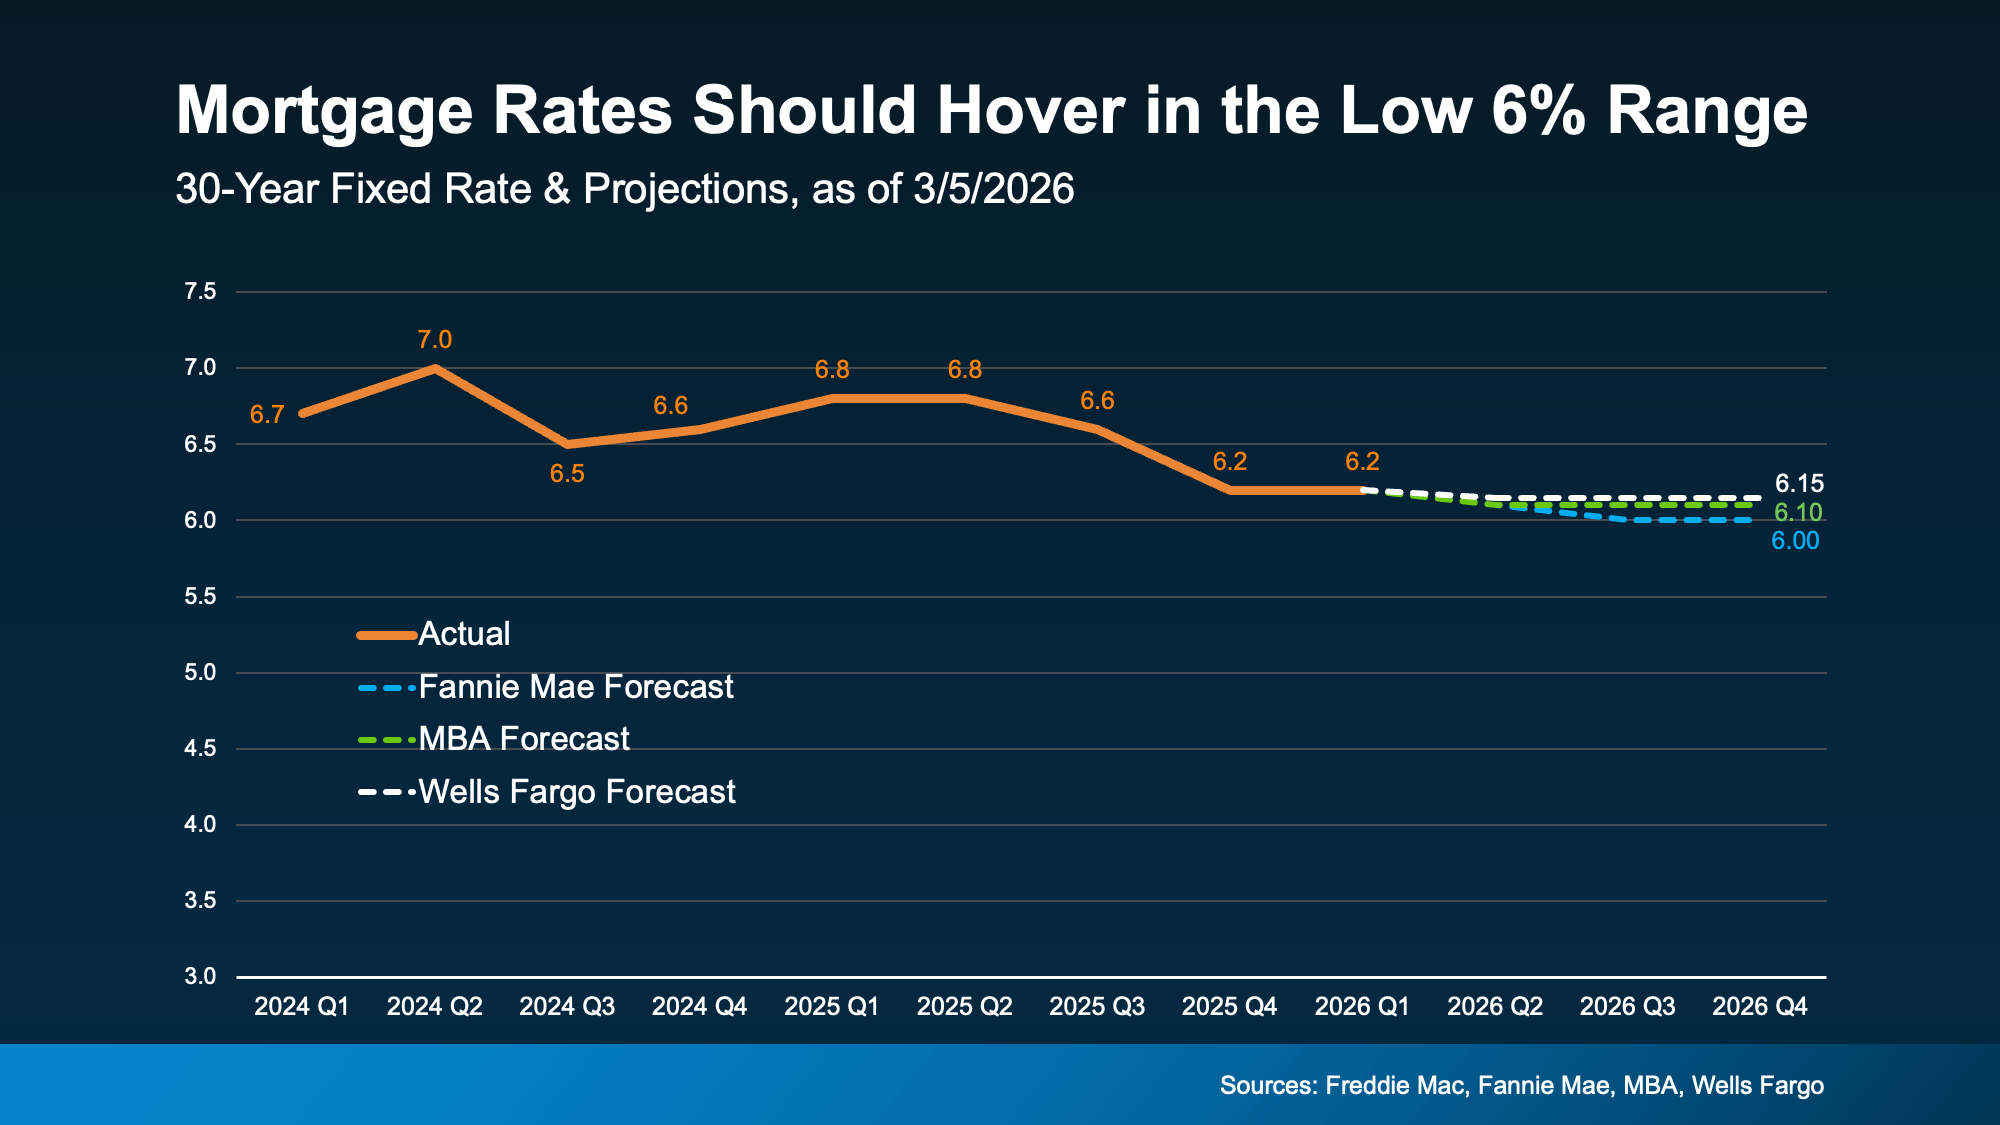
Another important piece to think about: most housing economists aren’t forecasting a long-term return to 5% territory anytime soon.

While rates will move up and down, likely hitting the high 5s here and there, the broader expectation is for mortgage rates to hover in the low 6% range this year, not stay in the 5’s or decline much more.

a graph with numbers and lines

While it certainly could happen, the reality is, waiting for a deep drop may not deliver the payoff you’re hoping for, if you’re holding out

The Bigger Question to Ask

Instead of asking, “Did I miss the 5s?” A better question is: “Does today’s payment work for me?”

If the monthly payment fits comfortably in your budget, and you’ve found a home that meets your needs, the difference between 6.1% and 5.9% likely isn’t the deciding factor. It might be one of them, but it shouldn’t be everything.

And remember, mortgage rates aren’t permanent. If they drop meaningfully later, refinancing is always an option. But you can’t refinance a home you didn’t buy.

Waiting Might Feel Safe, But It Isn’t Always Strategic

It’s natural to want the best possible rate. Everyone does. But sometimes buyers overestimate how much a rate in the high 5s will change things in today’s market.

Don’t miss the fact that rates have already come down. A year ago, they were in the 7s. Now? They’re hovering in the low 6s. And for a lot of people, that percentage point difference that’s already here is the real game changer.

If you paused your plans when rates were higher, now may be the right time to re-run your numbers. Not because rates are “perfect.” But because the monthly payment math might work better than you think, even with rates in the low 6s.

Before assuming you’ve missed your moment, take another look at the numbers.

You may find it never disappeared.

Bottom Line

If you’ve been sitting on the sidelines waiting for that magic number for rates, that strategy may not pay off as much as you’d expect.

Let’s connect so you can double check the math at your price point. You may realize payments are already within your range.

Source: https://www.simplifyingthemarket.com/en/2026/03/09/should-you-wait-for-lower-rates?a=5256-fd674d1a840c47baa4da566e9ff662ab

Why So Many Homeowners Are Downsizing Right Now

Why So Many Homeowners Are Downsizing Right Now

For a growing number of homeowners, retirement isn’t some distant idea anymore. It’s starting to feel very real.

According to Realtor.com and the Census, nearly 12,000 people will turn 65 every day for the next two years. And the latest data shows as many as 15% of those older Americans are planning to retire in 2026. And another 23% will do the same in 2027.

If you’re considering retiring soon too, here’s what you should be thinking about.

Why Downsize?

Now’s the perfect time to reflect on what you want your life to look like in retirement. Because even though your finances will be going through a big change, you don’t necessarily want to feel like you’re living with less.

But odds are, what you do want is for life to feel easier.

Easier to enjoy.

Easier to manage.

Easier to maintain day-to-day.

The Top Reasons People Over 60 Move

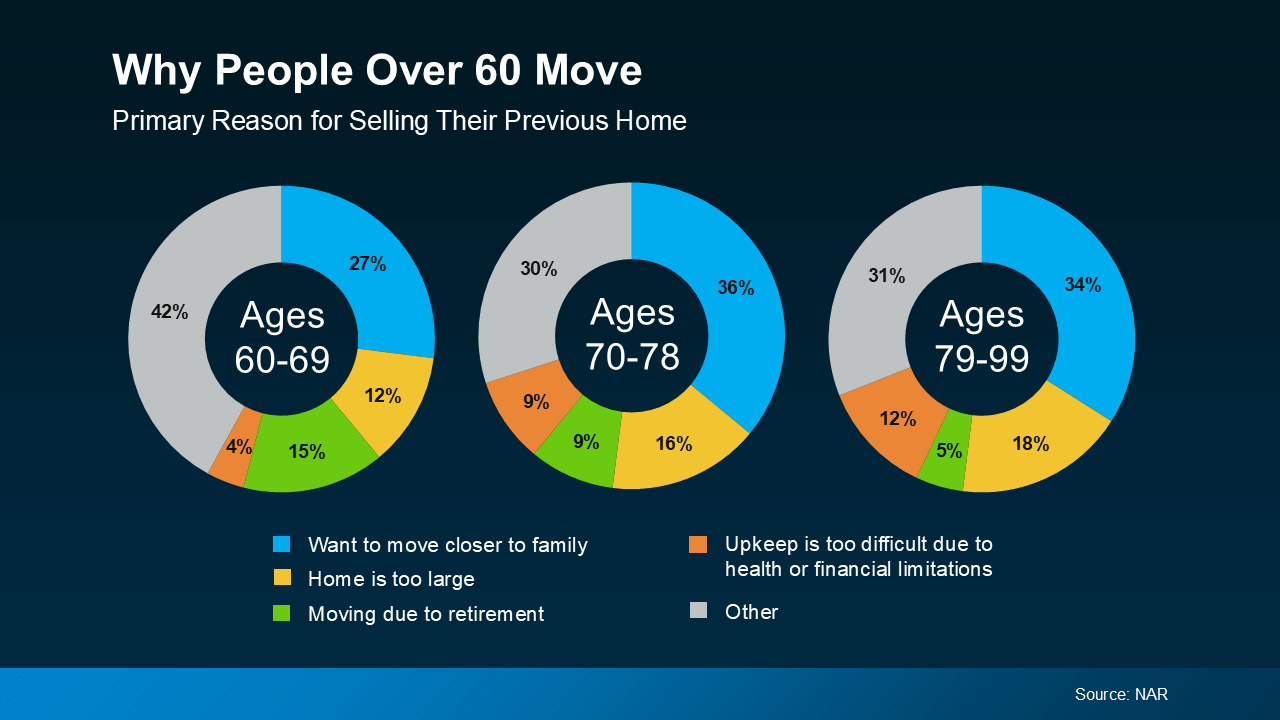
You can see these benefits show up in the data when you look at why people over 60 are moving. The National Association of Realtors (NAR) finds the top 4 reasons aren’t about timing the market or chasing top dollar. They’re about lifestyle:

  • Being closer to children, grandchildren, or long-time friends so it’s easier to spend more time with the people who matter most
  • Wanting a smaller, more functional home with fewer stairs and easier upkeep
  • Retiring and no longer needing to live near the office, so it’s easier to move wherever you want
  • Opting for something smaller to reduce monthly expenses tied to utilities, insurance, and maintenance

a graph of age groups

No matter the reason, the theme is the same: downsizing isn’t about giving something up. It’s about gaining control and choosing simplicity. And it brings peace of mind to know your home fits the years ahead, not the years behind.

And the best part? It’s more financially feasible now than many homeowners would expect.

The #1 Thing Helping So Many Homeowners Downsize

Here’s the part that makes it possible. Thanks to how much home values have grown over the years, many longtime homeowners are realizing they’re in a stronger position than they thought to make that move.

According to Cotality, the average homeowner today has about $299,000 in home equity. And for older Americans, that number is often even higher – simply because they’ve lived in their homes longer.

When you stay in one place for years (or even decades), two things happen at the same time:

  • Your home value has time to grow.
  • Your mortgage balance shrinks or disappears altogether.

That combination creates more options than you’d expect, even in today’s market.

So, whether you just retired, or you’re about to, it’s not too soon to start thinking about what comes next. Sure, it can be hard to leave the house you made so many years of memories in, but maybe it’s time to close one chapter to open a new one that’s just as exciting.

Bottom Line

Downsizing is about setting yourself up for what comes next – on your terms.

If retirement is on the horizon and you’ve started wondering what your current house (and your equity) could make possible, the first step isn’t selling. It’s understanding your options.

Let’s talk. A simple, no-pressure conversation can help you see what downsizing might look like – and whether it makes sense for you.

Source: https://www.simplifyingthemarket.com/en/2026/01/29/why-so-many-homeowners-are-downsizing-right-now?a=5256-fd674d1a840c47baa4da566e9ff662ab

Expert Forecasts Point to Affordability Improving in 2026

Expert Forecasts Point to Affordability Improving in 2026

Wondering what to expect from the housing market in 2026? You’re not the only one. For the past few years, affordability has been the biggest barrier standing between most people and their next move. And a lot of buyers and sellers have been holding their breath waiting for things to get better. The good news? It’s finally happening.

In 2025, affordability was the best it’s been in 3 years. And experts agree the momentum will keep going in 2026. And that’s based on their analysis of the key factors shaping the housing market in the year ahead: mortgage rates, inventory, and home prices.

Lower Mortgage Rates Are Already Here 

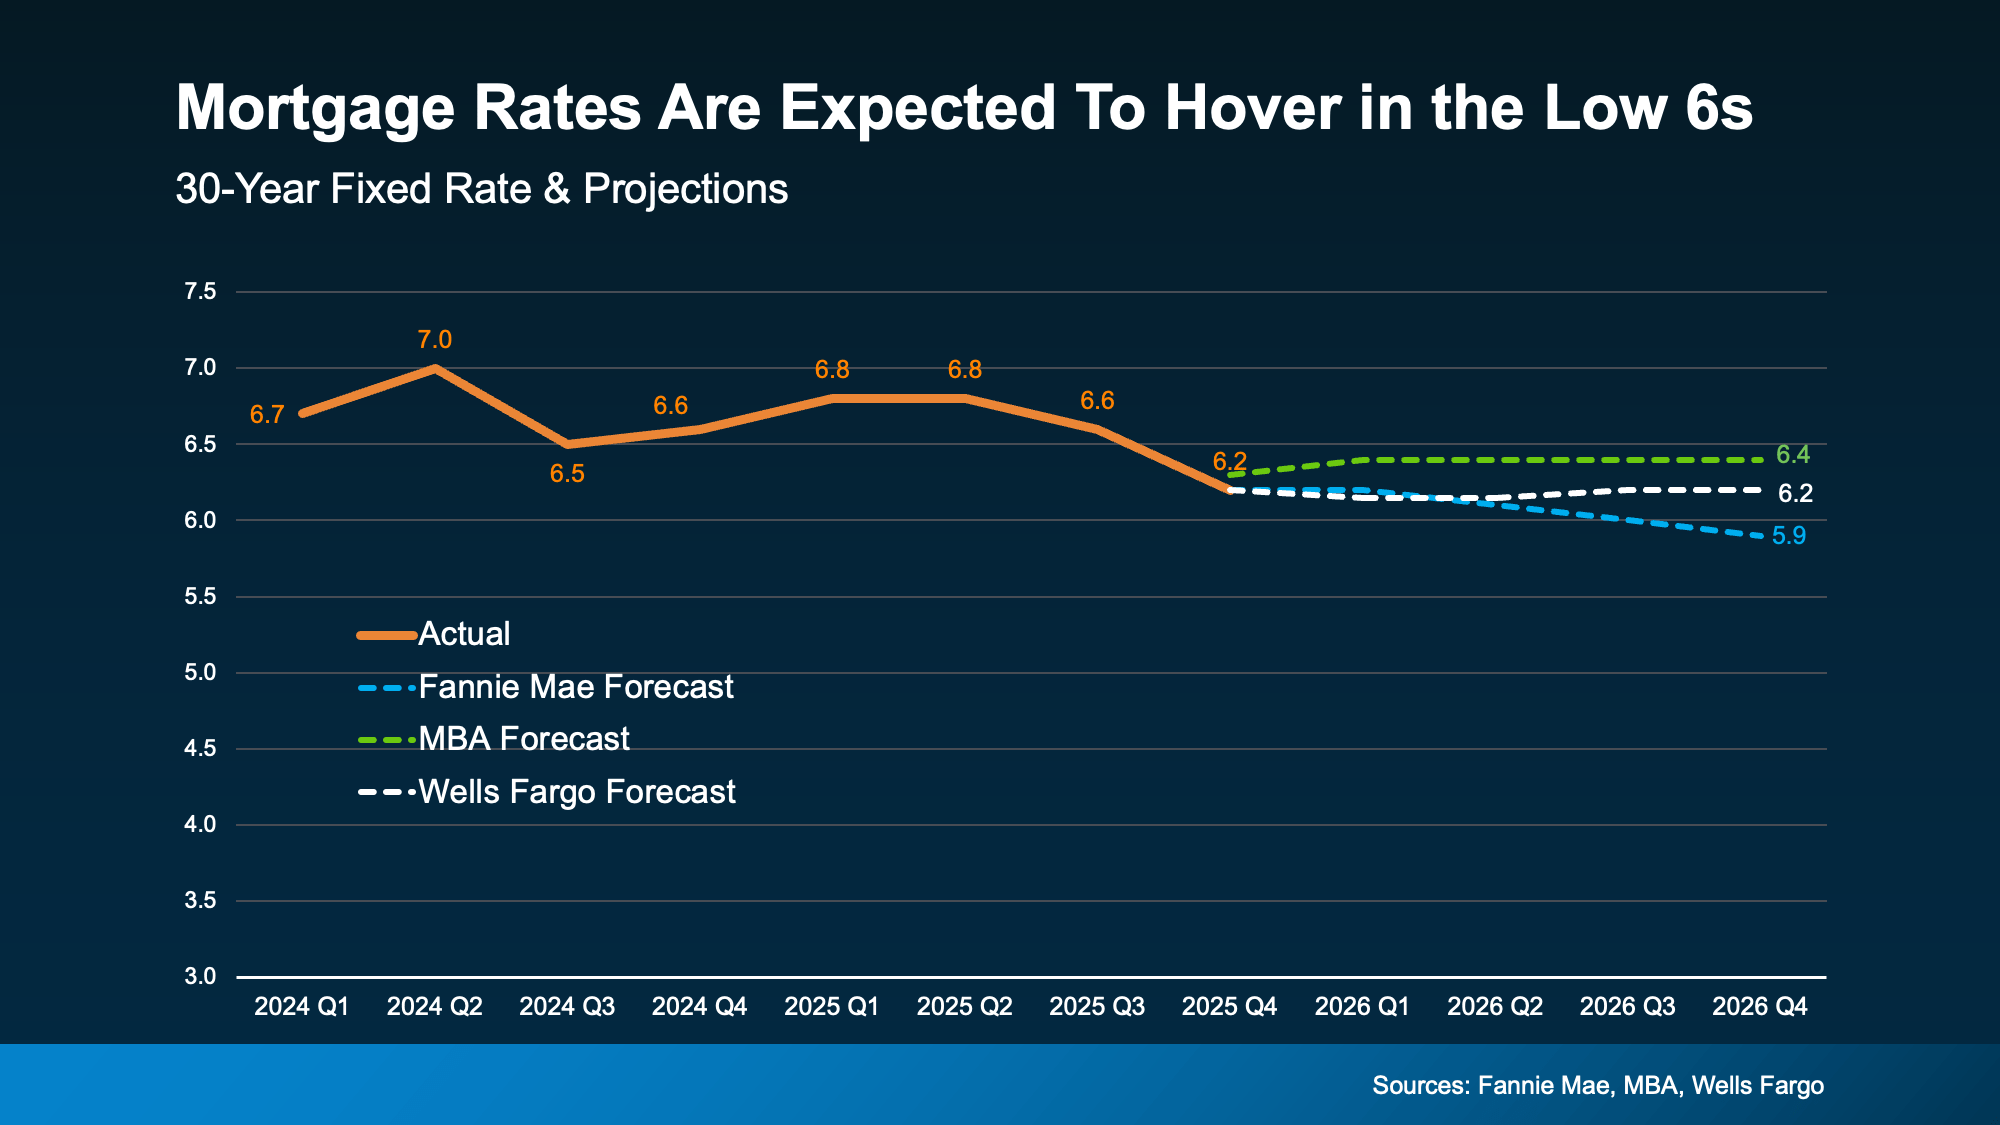
Mortgage rates have already come down from their peak. By some counts, they dropped by almost a full percentage point over the course of the last year. And that’s a big deal, even if it doesn’t sound like it. But how low will they go? And should you wait for them to come down more? Here’s your answer.

Forecasts suggest they’ll stay pretty much where they are now and hover in the low 6% range throughout 2026 (see graph below):

a graph with numbers and lines

Where they go from here really depends on what happens with the economy, the job market, and any changes in monetary policy the Fed makes in the year ahead. The important thing is, they’re already lower than they were just one year ago and that’s ideal if you’re planning a 2026 move.

  • For buyers: A lower rate reduces monthly payments and increases buying power. And, that combo helps more people qualify for homes that previously felt just out of reach.
  • For sellers: It may be time to accept that rates in the 6s are the new normal. And if you need to move, it’s doable, especially with your equity.

Even More Options Are on the Way

In 2025, the number of homes for sale improved by about 15%. As inventory rose, buyers regained things they hadn’t had in years: options, time to consider those options, and negotiating leverage. That helped restore more balance to the housing market.

Not to mention, the inventory gains are a big piece of what’s helped price growth slow down – which in turn improves affordability.

While the inventory gains this year aren’t expected to be as steep, experts at Realtor.com say the supply of homes for sale should grow by another 8.9% this year.

  • For buyers: That means even more choice and more negotiating power.
  • For sellers: Pricing your house right will be essential to draw in buyers.

Home Price Growth Is Slowing to a More Sustainable Pace

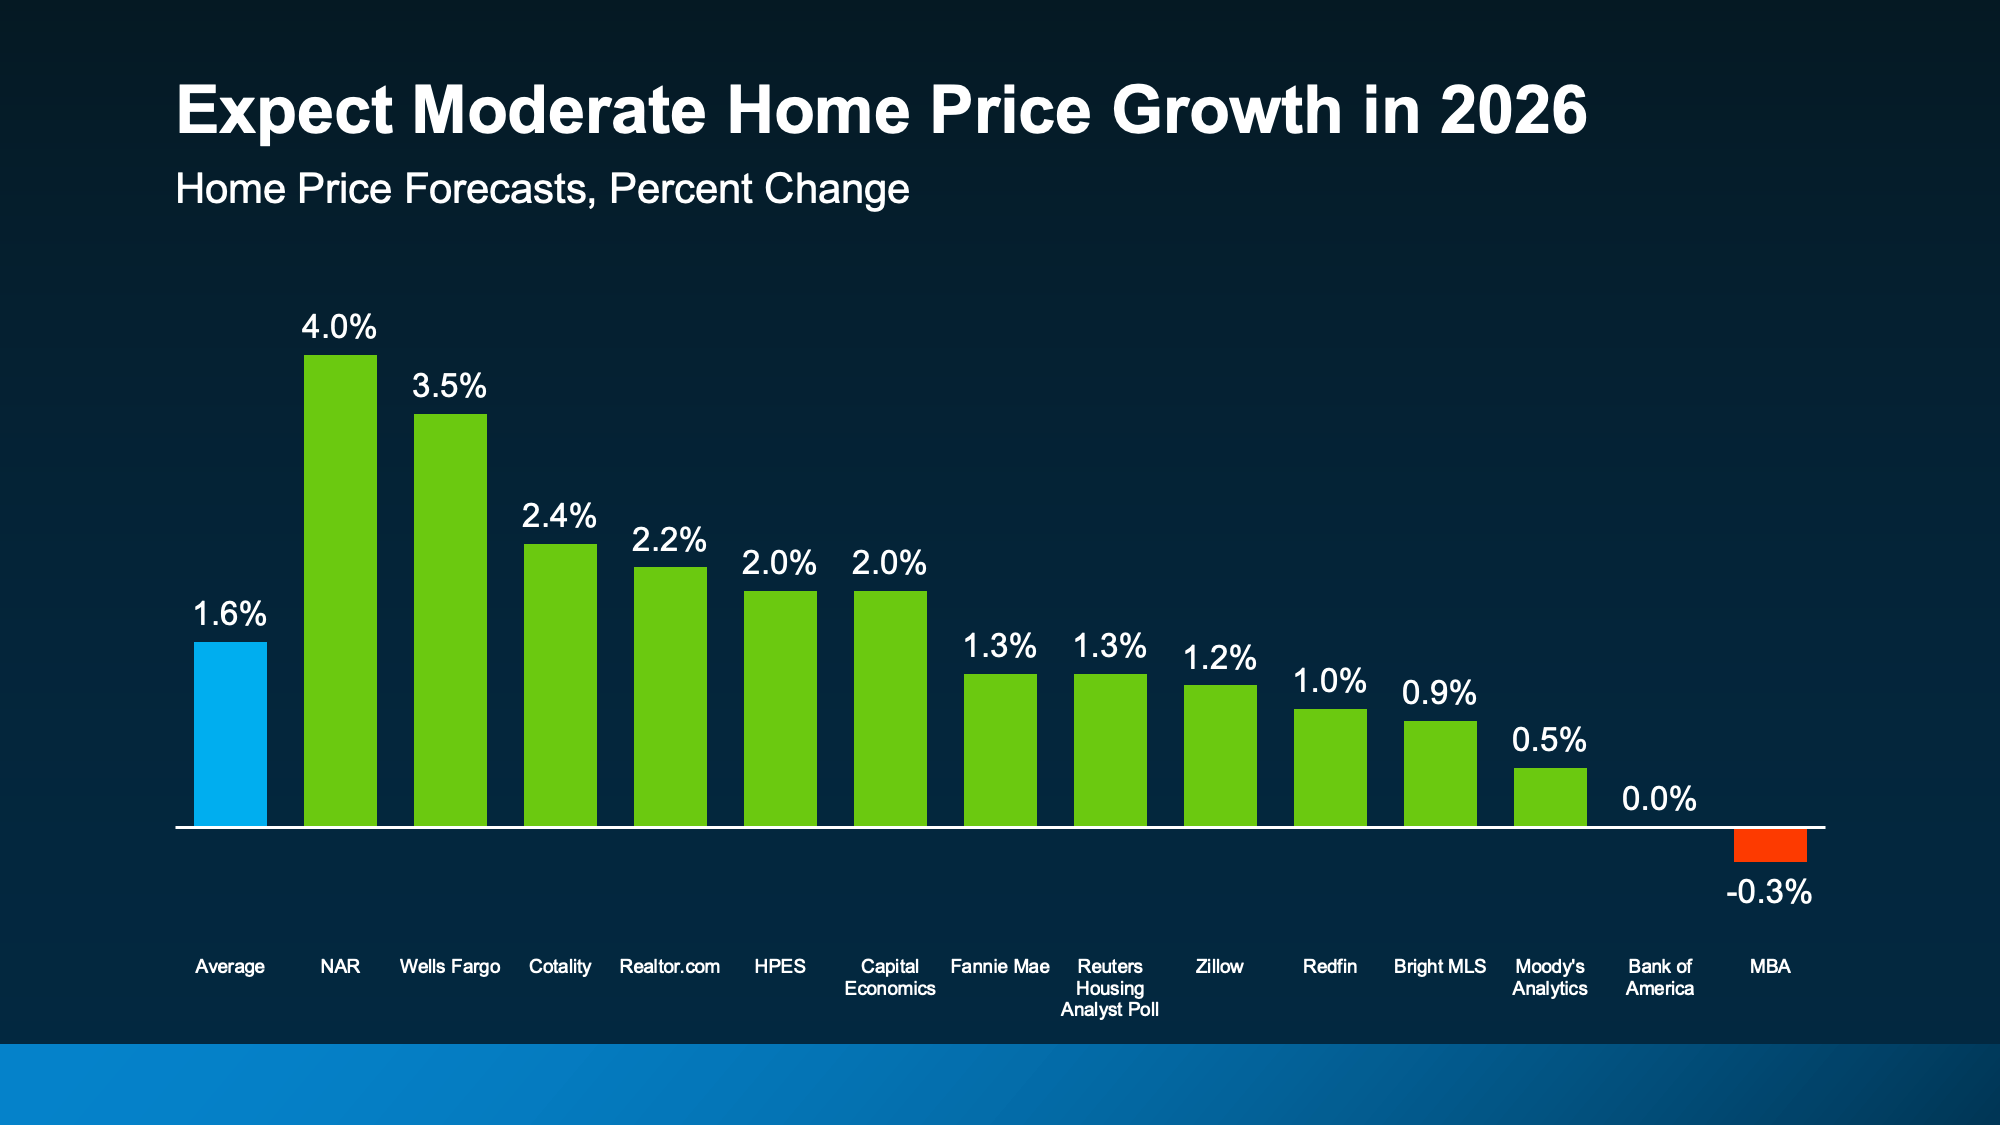
With more homes for sale, there isn’t as much upward pressure on prices right now. And we’ve seen that shake out over the past year. Even so, the overwhelming majority of experts say, nationally, prices will continue rising in the year ahead – just at a slower pace. On average, they say prices will rise by 1.6% in 2026 (see graph below):

a graph of increasing prices

And that’s reassuring if you’ve been fed content on social media saying prices are going to come crashing down. But here’s what you need to remember most about this. It’s going to vary a lot by area.

So, lean on a local agent for the latest on what’s happening where you are. Some markets will see prices rise more than this. Others may see prices come down slightly. It really all depends on conditions in your local market

But overall, prices will continue to rise at the national level. And that’s good for the market as a whole. As Realtor.com explains:

“For homebuyers and sellers, the shift signals a more balanced market—one where price growth steadies, rate relief offers breathing room, and negotiating power tilts subtly toward buyers.”

  • For buyers: Expect more moderate price growth, not the sudden and intense spikes just a few short years ago. That gives you fewer surprises and more predictability, which makes budgeting a whole lot easier.
  • For sellers: This slower price growth restores balance without putting your equity at risk. And that’s a win.

More Homes Will Sell 

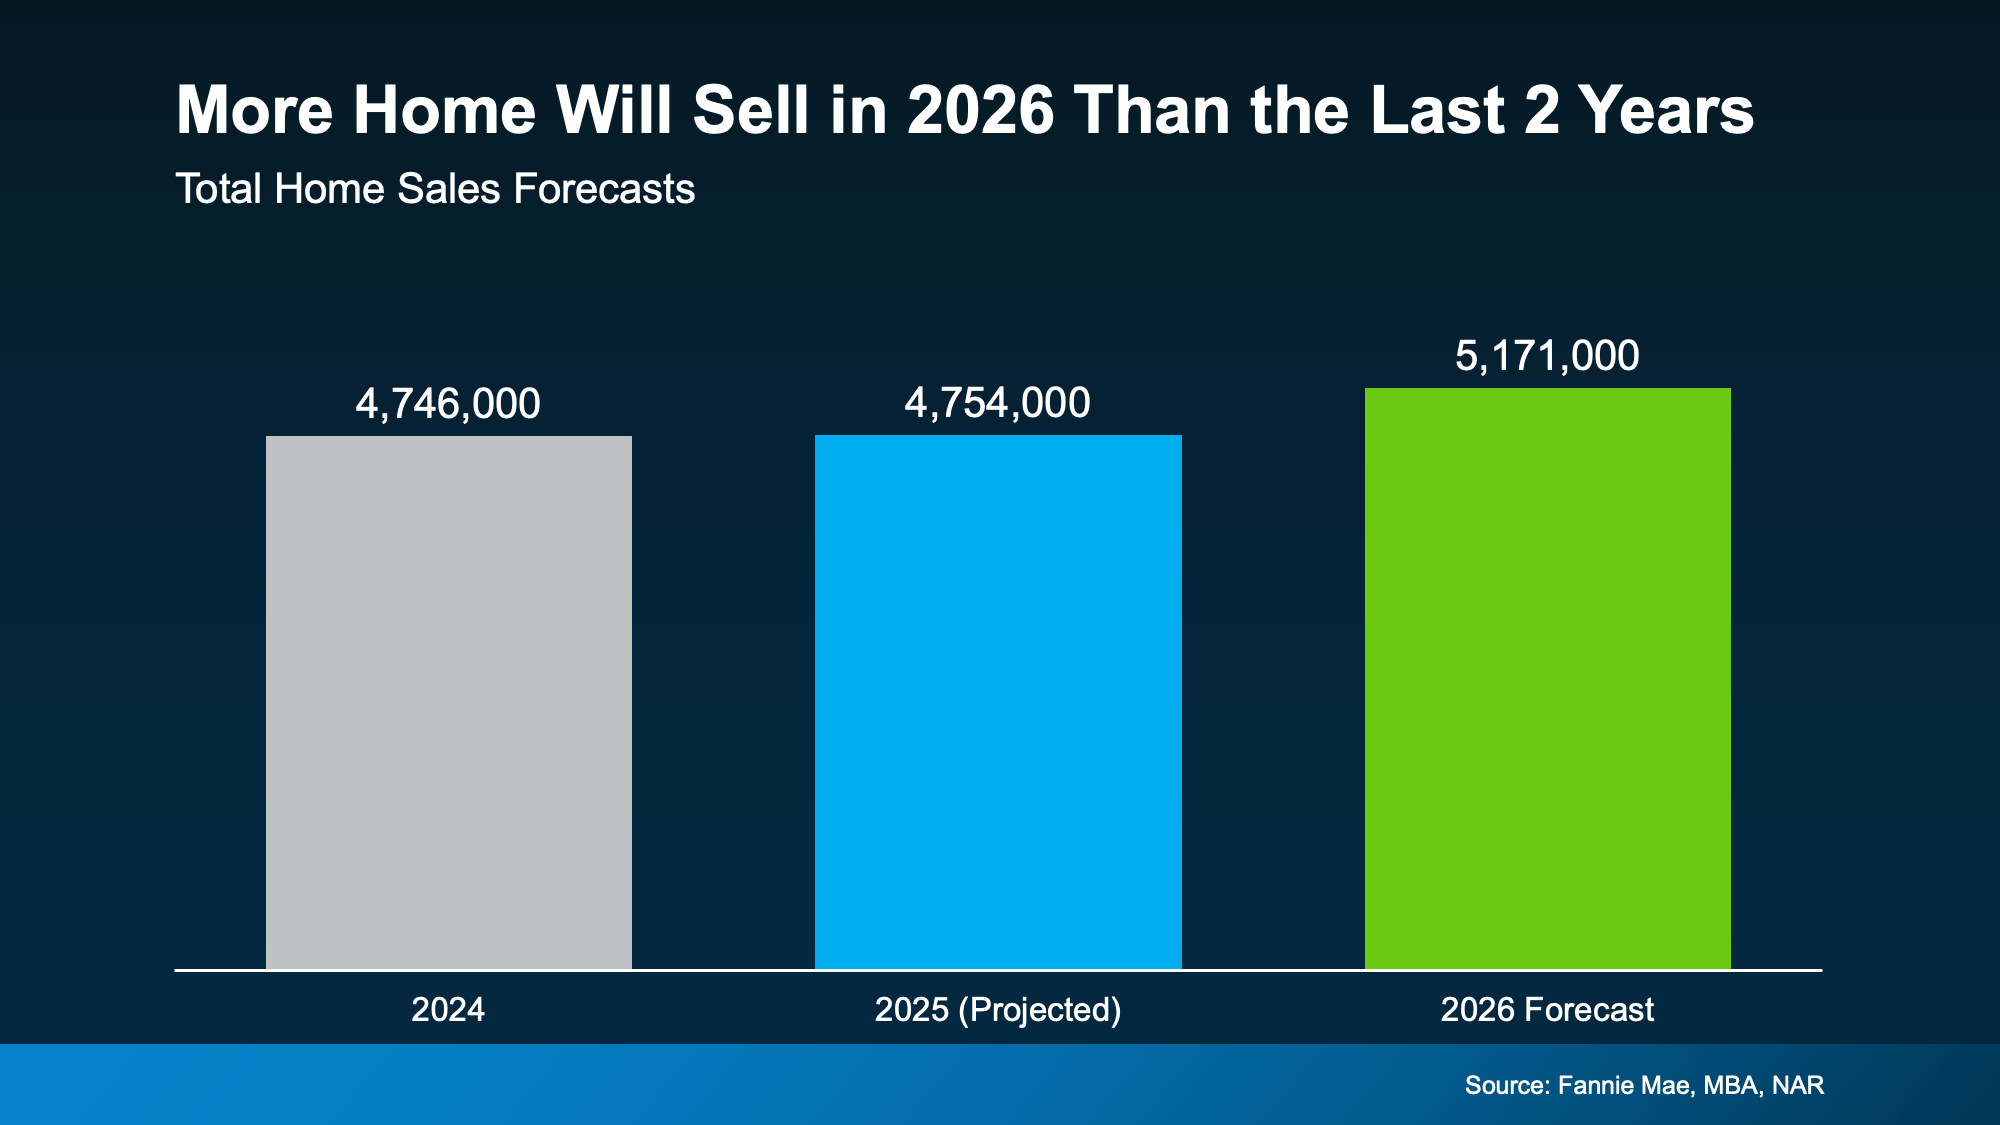
All of this adds up to a better affordability equation in 2026. And that’s exactly why experts are saying we should see more homes sell (and more people buy) this year.

a graph of a graph showing the sales of a company

As Mischa Fisher, Chief Economist at Zillow, says:

“Buyers are benefiting from more inventory and improved affordability, while sellers are seeing price stability and more consistent demand. Each group should have a bit more breathing room in 2026.”

The bottom line is, more people are finally going to be able to make their move this year. So, the question is: will you be one of them? The market is giving you an opportunity you haven’t had in a while. Maybe it’s time to take advantage of it.

Bottom Line

Affordability won’t change suddenly overnight. But, with several key trends working together, it should slowly and steadily improve in the months ahead.

That’s exactly why, in 2026, you should see a market with more balance, more predictability, and more breathing room than you’ve had in years.

Want more information about the opportunities unlocking in our local market?

Let’s chat.

Source: https://www.simplifyingthemarket.com/en/2026/01/08/expert-forecasts-point-to-affordability-improving-in-2026?a=5256-fd674d1a840c47baa4da566e9ff662ab